Home Loan Balance Transfer: Does It Pay?
A home loan is usually a long-term financial commitment. Over a tenure that may extend for 15, 20 or even 25 years, interest rates, borrower income, credit profile and lending conditions can change considerably.
A borrower who originally obtained a home loan at one interest rate may subsequently find another lender offering a lower rate. Moving the outstanding loan to the new lender can appear to be an obvious decision.
But a lower interest rate does not automatically make a balance transfer worthwhile.
The potential benefit depends upon several factors, including outstanding principal, difference in interest rates, remaining tenure, switching costs and the manner in which the resulting savings are utilised.
The appropriate question is therefore not simply:
“Is another lender offering me a lower rate?”
It is:
“Will transferring my remaining loan actually produce a meaningful financial benefit after considering all relevant costs and the remaining tenure?”
What Is a Home Loan Balance Transfer?
A home loan balance transfer involves transferring the outstanding balance of an existing home loan from the current lender to another lender.
In practical terms, the new lender evaluates the borrower and property, sanctions the eligible loan and uses the proceeds to repay the outstanding amount owed to the existing lender. The borrower subsequently services the transferred loan with the new lender under the new terms.
The property remains the underlying security, but the mortgage/security documentation and related processes are dealt with according to the requirements of the lenders and applicable law.
A balance transfer is therefore effectively a refinancing of the remaining home loan.
Why Do Borrowers Consider a Balance Transfer?
The most obvious reason is a lower interest rate.
But borrowers may also consider transferring because of:
- more favourable loan terms;
- better servicing experience;
- a different benchmark or spread;
- greater repayment flexibility;
- access to an eligible top-up facility;
- dissatisfaction with the existing lender; or
- a desire to restructure the remaining repayment period.
For most borrowers, however, the central economic question remains the potential interest saving.
The Original Loan Amount Is No Longer the Relevant Number
Suppose a borrower originally took:
₹80 lakh
as a home loan.
Several years later, the outstanding principal may have reduced to:
₹50 lakh
A balance-transfer decision should ordinarily be evaluated on the ₹50 lakh still outstanding, not the original ₹80 lakh.
This distinction matters because interest savings can only arise on the debt that remains to be repaid.
Similarly, the original tenure is less important than the remaining tenure.
A borrower who originally took a 20-year loan but has only four years remaining is in a very different position from someone with 15 years still to run.
A Worked Example: When the Rate Difference Matters
Consider a borrower with:
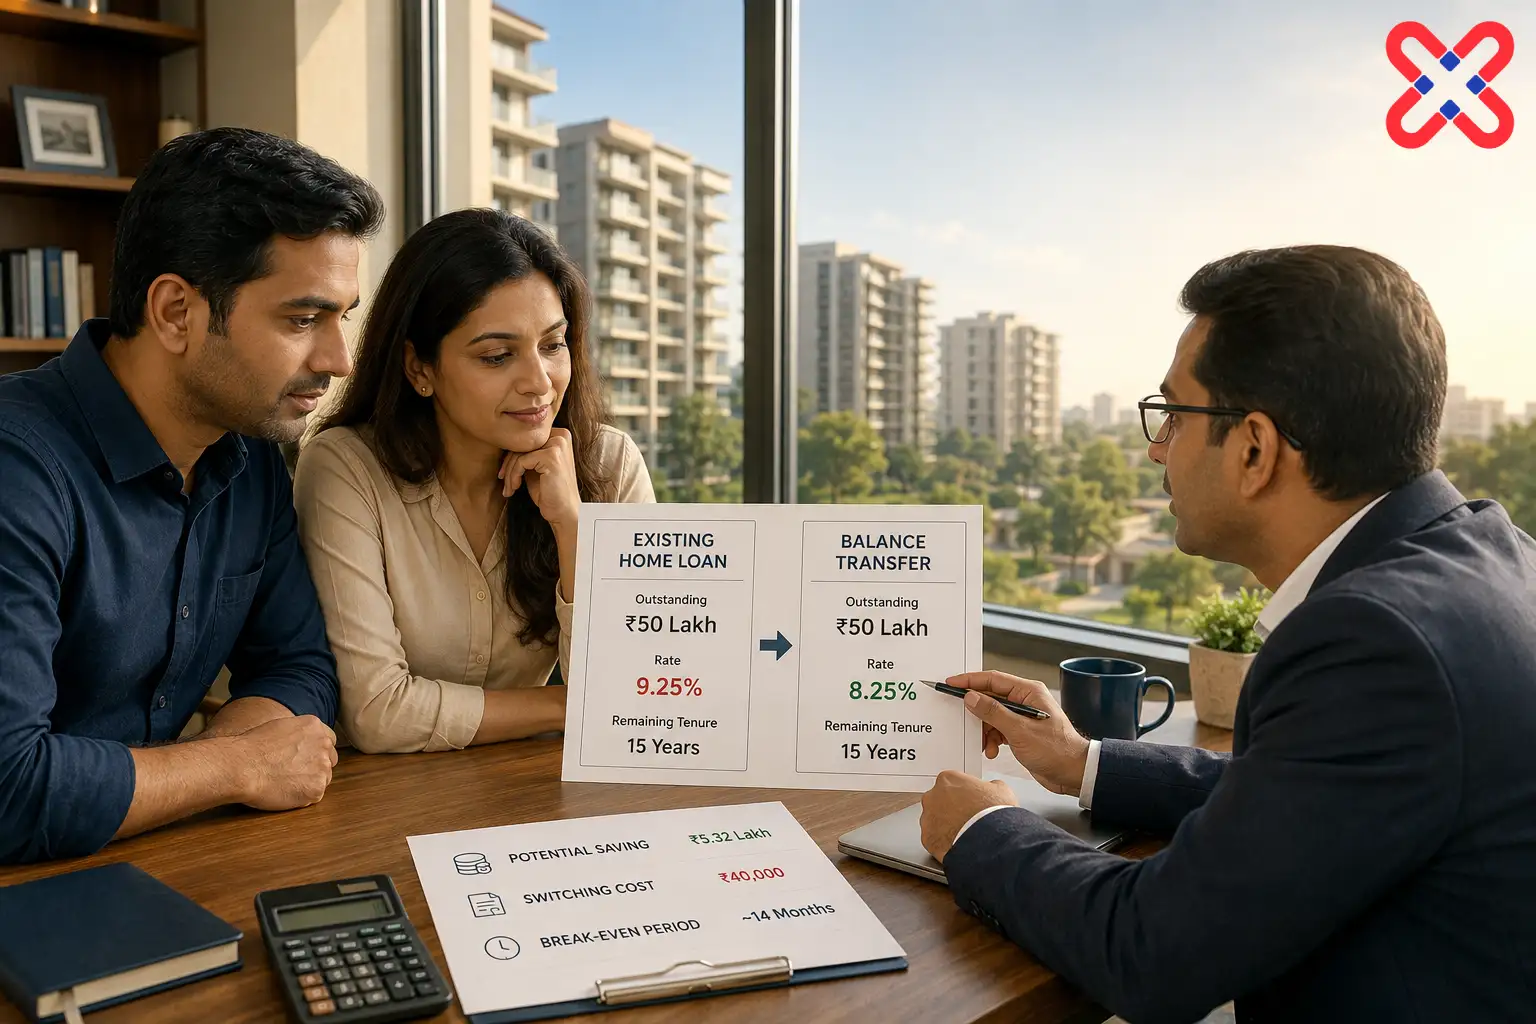
Outstanding principal: ₹50 lakh
Remaining tenure: 15 years
Existing interest rate: 9.25%
Proposed new rate: 8.25%
Assuming the rate remained unchanged throughout purely for illustration:
At 9.25%, the EMI would be approximately:
₹51,460 per month
At 8.25%, the EMI would be approximately:
₹48,507 per month
The monthly difference is approximately:
₹2,953
That may not initially appear dramatic.
But over a long remaining tenure, the cumulative effect can become substantial.
Approximate interest over the remaining 15 years at 9.25%:
₹42.63 lakh
Approximate interest at 8.25%:
₹37.31 lakh
Indicative interest difference:
approximately ₹5.32 lakh
A one-percentage-point reduction, applied to a meaningful outstanding balance over a long period, can therefore potentially create significant savings.
These calculations are simplified illustrations assuming unchanged rates and regular repayments. Actual floating rates, repayment schedules and outcomes can differ.
But the ₹5.32 Lakh Is Not Automatically the Net Saving
Transferring a loan can involve costs.
Depending upon the lender, property, state and transaction, these may include:
- processing charges;
- legal scrutiny;
- property valuation;
- administrative charges;
- mortgage-related documentation;
- stamp duty or registration-related costs where applicable;
- CERSAI or other statutory charges; and
- other applicable expenses.
For example, HDFC Bank’s published balance-transfer schedule currently includes processing charges and identifies stamp duty, registration and other statutory charges as applicable; other lenders can have different fee structures.
Suppose the total incremental cost of completing our hypothetical transfer is:
₹40,000
The simplified potential net benefit becomes:
₹5.32 lakh – ₹40,000 = approximately ₹4.92 lakh
That begins to provide a much more meaningful basis for the decision.
Break-Even: How Long Before the Transfer Pays for Itself?
Another useful concept is the break-even period.
Return to our example:
Approximate monthly EMI reduction: ₹2,953
Illustrative transfer cost: ₹40,000
A simple calculation gives:
₹40,000 ÷ ₹2,953 = approximately 14 months
On this simplified basis, the borrower would recover the switching cost through the EMI difference in roughly 14 months.
If the borrower expects to retain the loan substantially longer than that, the transfer may deserve serious consideration.
If the borrower expects to sell the property or repay the loan completely within six months, the economics could look very different.
This is why a balance transfer should not be assessed only through the headline rate difference.
Remaining Tenure Can Change the Answer
Consider another borrower:
Outstanding loan: ₹20 lakh
Remaining tenure: 4 years
Existing rate: 9.25%
New rate: 8.25%
At 9.25%, the approximate EMI is:
₹50,008
At 8.25%, it is approximately:
₹49,061
The monthly difference is only about:
₹947
Approximate remaining interest at 9.25%:
₹4.00 lakh
Approximate remaining interest at 8.25%:
₹3.55 lakh
Potential interest saving:
approximately ₹45,000
Now suppose transferring the loan costs ₹35,000.
The approximate net financial saving could fall to only:
₹10,000
Despite the same 1% interest-rate reduction, the economic benefit is dramatically smaller than in our earlier example.
Why?
Because considerably less principal and much less tenure remain.
This illustrates an important principle:
The same reduction in interest rate can have very different value for different borrowers.
Earlier in the Loan, Interest Savings Can Be More Powerful
Home loans generally follow an amortising repayment structure.
In the earlier years, a relatively larger portion of each EMI typically goes towards interest. As the loan progresses, the interest component generally reduces while a greater proportion goes towards principal.
This means a borrower with:
₹60 lakh outstanding and 17 years remaining
may have considerably more to gain from a meaningful rate reduction than another borrower with:
₹10 lakh outstanding and two years remaining.
Therefore, the stage of the loan is an important part of the transfer decision.
EMI Reduction or Tenure Reduction?
This is one of the most important choices after obtaining a lower interest rate.
Return to our ₹50 lakh example.
At 9.25% for 15 years:
EMI ≈ ₹51,460
After transferring to 8.25%, the borrower could reduce the EMI to approximately:
₹48,507
and continue for 15 years.
That provides monthly cash-flow relief of approximately ₹2,953.
But there is another possibility.
Suppose the borrower can comfortably continue paying approximately the old EMI of ₹51,460, despite receiving the lower 8.25% rate.
Instead of using the rate reduction to lower the EMI, the borrower can effectively accelerate repayment.
On our simplified assumptions, maintaining roughly the old EMI at the new rate could repay the loan in approximately:
161 months instead of 180 months
or about:
13 years and 5 months instead of 15 years.
That is roughly 19 months earlier.
This demonstrates a powerful distinction:
Lower rate + lower EMI = improved monthly cash flow
while
Lower rate + same EMI = potentially faster debt repayment and greater interest saving
Neither is universally better. The appropriate choice depends upon the borrower’s cash-flow needs and financial priorities.
A Lower EMI Can Sometimes Be Misleading
Suppose a lender says:
“Transfer your loan and reduce your EMI substantially.”
That sounds attractive.
But what if the lower EMI is achieved partly by extending the tenure?
Consider a borrower with ten years remaining who transfers the loan and resets the tenure to 15 years.
The monthly EMI may fall considerably.
But the borrower will also continue paying interest for another five years.
A lower EMI therefore does not necessarily mean a lower overall borrowing cost.
Always compare:
Outstanding Principal + Interest Rate + Remaining Tenure + Total Repayment
not EMI alone.
Ask Your Existing Lender First
Before transferring the loan, it may be worthwhile asking the existing lender whether the interest rate can be reduced.
The lender may, depending upon its policies and the loan, offer:
- conversion to a lower applicable rate;
- adjustment of spread;
- migration to another benchmark;
- a revised loan product; or
- another permitted repricing arrangement.
There may be a conversion or administrative charge, but if the existing lender can offer a sufficiently competitive rate, the borrower could potentially avoid the documentation, property verification and administrative process associated with moving to another institution.
Consider:
Existing rate: 9.25%
New lender: 8.25%
But after discussion, the existing lender offers:
8.40%
The remaining difference is now only:
0.15 percentage points
At that stage, transferring to another lender may no longer provide sufficient incremental benefit after considering switching costs and effort.
The correct comparison has changed from:
9.25% vs 8.25%
to:
8.40% vs 8.25%
That is a very different decision.
Credit Profile Can Influence the New Offer
A borrower who took a home loan several years ago may have a different financial profile today.
Perhaps:
- income has increased;
- repayment history is strong;
- credit score has improved;
- existing liabilities have reduced; or
- the property’s value has increased.
These factors may improve the borrower’s attractiveness to competing lenders.
Conversely, deteriorating credit quality, increased debt or irregular repayment history may restrict the terms available.
A balance-transfer advertisement therefore does not guarantee that every borrower will receive the advertised rate.
The new lender will undertake its own credit assessment.
The Property Is Evaluated Again
A balance transfer is not merely a rate switch in a computer system.
The new lender is taking security over the property and therefore ordinarily needs to satisfy itself regarding the property and associated documentation.
Depending upon the lender and case, this can involve:
- legal scrutiny;
- title verification;
- technical assessment;
- property valuation;
- documentation review; and
- mortgage/security formalities.
A borrower should therefore account for both time and transaction costs.
Floating Rates Can Change Again
Suppose a borrower transfers from:
9.25% to 8.25%
and assumes that the 1% advantage will continue for the next 15 years.
That may not necessarily happen if the new loan is floating-rate.
The applicable benchmark can change.
The existing and new lenders may also have different benchmark structures and spreads.
The borrower should therefore understand:
What benchmark is the new loan linked to?
What is the spread over that benchmark?
How frequently can the rate reset?
Under what circumstances can the spread change?
What happens to EMI or tenure when rates change?
RBI’s framework for floating-rate EMI-based personal loans requires regulated entities to communicate the impact of rate resets and provide borrowers with specified options, including changes to EMI/tenure, switching to fixed rates under the lender’s policy, and part or full prepayment.
Prepayment and Foreclosure Charges
This is an area where borrowers should avoid relying on old assumptions.
RBI has progressively restricted foreclosure/prepayment charges on floating-rate loans to individual borrowers. For floating-rate home loans from banks, RBI had already prohibited foreclosure/prepayment penalties, and the broader Pre-payment Charges on Loans Directions, 2025 further standardised the framework for loans sanctioned or renewed from January 1, 2026.
However:
No foreclosure penalty does not mean zero balance-transfer cost.
The new lender can still have applicable processing, legal, valuation, mortgage, statutory or other permitted charges.
The borrower should therefore obtain the complete cost of transferring, rather than asking only:
“Does my existing lender charge foreclosure?”
Compare APR and the Key Fact Statement
The nominal interest rate is only one component of borrowing cost.
Applicable fees and charges can materially affect the economics.
RBI guidance encourages borrowers to consider the Annual Percentage Rate (APR), which incorporates the interest rate and applicable charges in a standardised annualised measure.
Where applicable, borrowers should examine the lender’s Key Fact Statement (KFS) and relevant loan documentation carefully.
This makes comparisons more meaningful than simply comparing two advertised interest rates.
Should You Take a Top-Up at the Same Time?
A new lender may offer a top-up loan alongside the balance transfer.
For example:
Existing outstanding home loan: ₹50 lakh
Eligible balance transfer: ₹50 lakh
Additional top-up offered: ₹20 lakh
The borrower may therefore be offered total financing of:
₹70 lakh
This does not mean taking the additional ₹20 lakh is financially beneficial.
If the borrower genuinely requires funds for an appropriate purpose and the economics are suitable, a top-up may be useful.
But taking additional debt merely because it is available increases:
- outstanding principal;
- interest cost;
- repayment obligation; and
- potentially the time required to become debt-free.
A balance transfer intended to reduce borrowing cost should not inadvertently become an excuse to increase unnecessary borrowing.
Example: When a Balance Transfer Can Make Sense
Consider:
Outstanding principal: ₹60 lakh
Remaining tenure: 16 years
Current rate: 9.40%
New rate: 8.25%
The borrower:
- has a strong repayment record;
- intends to retain the loan for many years;
- receives a meaningful rate reduction;
- has reasonable switching costs; and
- does not extend the tenure unnecessarily.
Here, the combination of a large outstanding balance + meaningful rate difference + long remaining tenure can make the potential savings substantial enough to justify evaluating the transfer seriously.
Example: When It May Not Make Sense
Now consider:
Outstanding principal: ₹12 lakh
Remaining tenure: 2 years
Current rate: 9.00%
New rate: 8.25%
The headline says:
“Save 0.75%.”
But only ₹12 lakh remains outstanding and the loan will finish in two years.
After considering:
- processing charges;
- legal/technical expenses;
- applicable mortgage-related costs;
- administrative effort; and
- the short period over which the lower rate will apply,
the actual benefit may be modest.
In this situation, a rate reduction that looks attractive in percentage terms may have limited economic value in rupee terms.
Example: The Lowest Rate Is Not Necessarily the Best Offer
Suppose three options are available:
Existing lender: 8.75% with no action required.
Lender A: 8.35% with ₹15,000 total incremental switching costs.
Lender B: 8.20% with ₹60,000 total incremental switching costs.
Lender B has the lowest headline rate.
But whether it is the best choice depends upon:
- outstanding balance;
- remaining tenure;
- incremental interest saving;
- additional ₹45,000 cost versus Lender A; and
- how long the borrower expects to keep the loan.
The lowest rate therefore needs to produce enough additional saving to compensate for its additional cost.
What About the Time and Effort?
Not every relevant cost appears in rupees.
A balance transfer may involve:
- obtaining documents from the existing lender;
- submitting financial information;
- property verification;
- legal review;
- valuation;
- sanction formalities;
- coordination between lenders; and
- execution of new documentation.
For a potential saving of several lakh rupees, this effort may be entirely reasonable.
For a net saving of ₹10,000 over several years, a borrower may reach a different conclusion.
Financial optimisation should remain economically meaningful, not merely mathematically positive.
A Simple Decision Framework
Before transferring a home loan, a borrower can evaluate six questions:
1. Outstanding Principal
How much loan is actually left?
2. Remaining Tenure
For how many years will the lower rate provide a benefit?
3. Rate Difference
How meaningful is the reduction?
4. Total Switching Cost
What will the transfer actually cost?
5. Break-Even Period
How long before those costs are recovered?
6. Expected Holding Period
Will the loan remain outstanding long enough to realise the expected savings?
These six questions can eliminate many apparently attractive but economically weak transfer propositions.
Questions to Ask the New Lender
Before accepting a balance-transfer offer, understand:
Interest Rate — What rate is actually being offered to you?
Benchmark — What is it linked to?
Spread — What spread applies over the benchmark?
Reset — How and when can the rate change?
EMI — What will the revised monthly payment be?
Tenure — Is the tenure being retained, reduced or extended?
Total Interest — What is the expected interest over the remaining term under the stated assumptions?
Processing Fee — What does the lender charge?
Legal and Valuation Costs — Are these additional?
Mortgage/Statutory Costs — What other charges may apply?
Prepayment — What conditions apply if you later repay early?
Top-Up — Is additional borrowing genuinely required?
Documentation — What will be required from the borrower and existing lender?
The objective is to compare the complete economics, not merely the first number in an advertisement.
The Broader Perspective
A home loan balance transfer can be an effective financial decision when a meaningful interest-rate reduction is applied to a substantial outstanding balance over a sufficiently long remaining tenure.
But refinancing is not valuable simply because the new rate is lower.
A disciplined borrower should compare:
Old Rate vs New Rate
but also:
Remaining Principal + Remaining Tenure + Switching Costs + Break-Even + Total Interest
And where the borrower can comfortably maintain the existing EMI after obtaining a lower rate, using the benefit to shorten the tenure rather than merely reduce the monthly payment can potentially accelerate the journey towards becoming debt-free.
The central question is therefore not:
“Can I transfer my home loan at a lower rate?”
It is:
“After every relevant cost and the remaining tenure are considered, how much will I genuinely save—and is that saving meaningful enough to justify the transfer?”
That is the more appropriate basis for deciding whether a home loan balance transfer truly pays.
Looking to Discuss an Opportunity?
Connect with Magnet Capital Partners to discuss your requirements and explore how our advisory capabilities may assist.
Disclaimer
This article forms part of Insights — The Magnet Knowledge Series and is intended solely for general informational and educational purposes. It does not constitute investment, financial, legal, tax, regulatory, real estate or other professional advice, nor does it constitute an offer, solicitation, recommendation or assurance in relation to any investment, transaction, product, service or return.
Any information, views, examples, calculations, illustrations, scenarios, projections, estimates or references to valuations, yields, returns, interest rates, financial performance, market conditions or other quantitative or qualitative measures contained in this article are general or illustrative in nature. They should not be interpreted as actual, assured, promised or indicative future outcomes. Actual circumstances and outcomes may differ materially depending upon applicable facts, assumptions, market conditions, commercial considerations, regulatory requirements and other relevant factors.
Readers should undertake their own evaluation and obtain appropriate independent professional advice before making any investment, financial, business, transaction, real estate or other decision. Information contained in this article may change over time and may not reflect subsequent developments. Magnet Capital Partners makes no representation or warranty, express or implied, regarding the accuracy, completeness or continuing relevance of the information contained herein and accepts no liability arising from reliance upon or use of this article, to the extent permitted by applicable law.
Copyright
© Magnet Capital Partners. All rights reserved.
The original editorial content, organisation, structure and presentation of Insights — The Magnet Knowledge Series are protected by applicable copyright laws. No part of this article may be reproduced, republished, distributed, transmitted, adapted or commercially used, in whole or in substantial part, without the prior written permission of Magnet Capital Partners, except as permitted by applicable law. References to third-party information, data, regulations, concepts, terminology, trademarks or other materials remain subject to the rights of their respective owners, where applicable.