Credit Score: Effect on Loan Eligibility and Interest Rates
When applying for a loan, borrowers often focus on income, loan amount, tenure and the resulting EMI. Lenders, however, consider another important element while evaluating an application: the borrower’s credit profile.
A credit score provides a numerical representation of an individual’s credit history and creditworthiness. In India, lenders commonly use credit information and scores from credit information companies as part of their credit appraisal processes. A stronger credit profile can improve the prospects of approval and may also influence the terms on which credit is offered.
Understanding how credit scores work can therefore help borrowers approach financing decisions with greater awareness.
What Is a Credit Score?
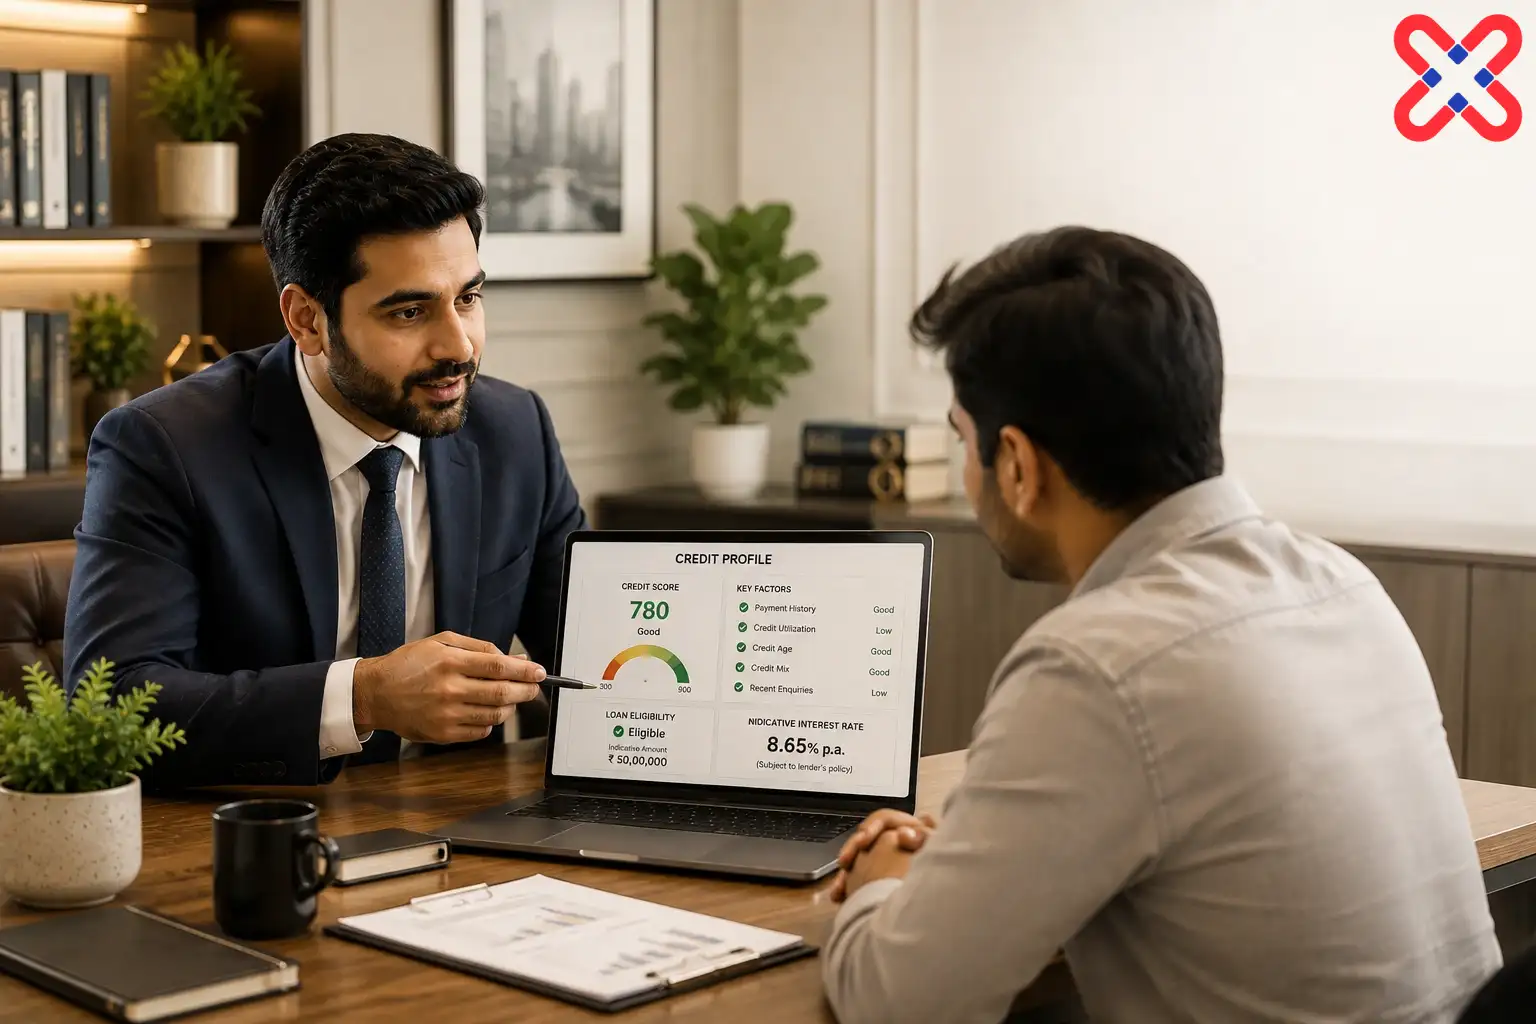
A credit score is a numerical summary derived from information contained in a borrower’s credit report. In the case of a CIBIL Score, it ranges from 300 to 900, with a higher score generally representing a stronger credit profile.
The underlying credit report contains information relating to borrowing and repayment behaviour, including loan and credit-card accounts, payment history, outstanding amounts and credit enquiries.
A credit score should not, however, be viewed in isolation. The final decision to approve a loan remains with the lender, which considers the score together with other eligibility and risk parameters.
How Credit Score Affects Loan Eligibility
When a borrower submits a loan application, lenders assess whether the applicant has the capacity and willingness to repay the proposed borrowing.
Credit history is an important part of this assessment.
A stronger credit score may indicate a history of responsible credit behaviour and can strengthen a loan application. Conversely, a weaker score may result in closer scrutiny, stricter lending terms or, in some cases, rejection of the application.
Importantly, a good credit score does not guarantee loan approval.
Lenders may additionally consider factors such as:
- income and employment or business stability;
- existing loan obligations;
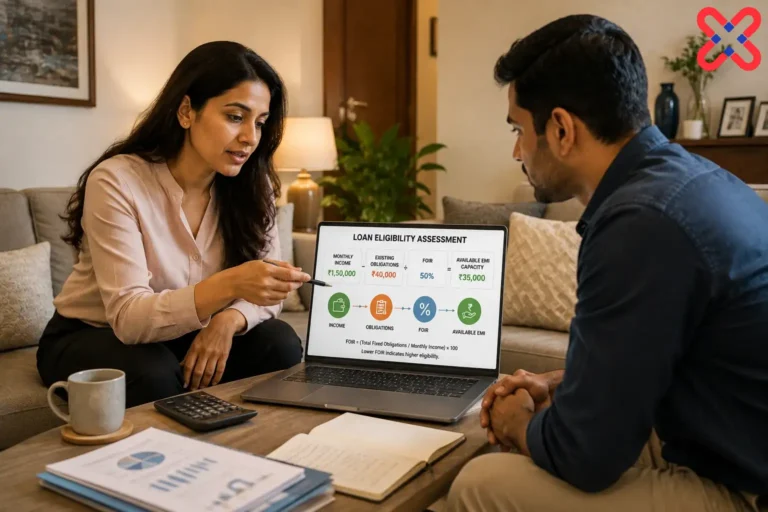
- EMI-to-income or FOIR considerations;
- loan amount and tenure;
- nature and value of security for secured loans;
- banking and repayment behaviour; and
- individual lender credit policies.
The relative importance of these factors can differ between lenders and loan products.
Can Credit Score Affect the Interest Rate?
Yes. Credit score can influence not only whether credit is available but also the terms on which a lender is prepared to provide it.
A borrower with a stronger credit profile generally represents a lower perceived credit risk. Depending on the lender’s pricing framework, this may result in access to more competitive interest rates or other favourable terms. A weaker profile may lead to higher rates, stricter conditions or additional evaluation.
However, there is no universal interest rate attached to a particular credit score.
Interest rates can also depend on the type of loan, income profile, loan amount, tenure, collateral, prevailing market conditions and the lender’s internal policies.
This is why two borrowers seeking similar loans may receive different offers.
What Can Affect Your Credit Score?
Credit-scoring methodologies are proprietary and can differ between credit information companies. RBI does not prescribe a single methodology for calculating credit scores.
Nevertheless, a borrower’s credit behaviour remains important. Factors reflected in credit reports can include repayment history, outstanding credit, utilisation of available credit and enquiries generated when applying for new credit.
For example, repeated applications for credit over a short period can result in multiple lender enquiries, while high utilisation of available credit may indicate greater dependence on borrowing. These factors can affect how a borrower’s overall credit profile is assessed.
Does a Low Credit Score Mean You Cannot Get a Loan?
Not necessarily.
A lower credit score can make borrowing more difficult, but it does not automatically mean that every lender will reject an application.
A lender may consider the borrower’s overall circumstances and could offer a lower loan amount, higher interest rate, additional conditions or a different structure depending on the loan and its credit policy.
For secured borrowing, the nature and value of the underlying security may also form part of the assessment, although the borrower’s repayment capacity and credit history remain relevant.
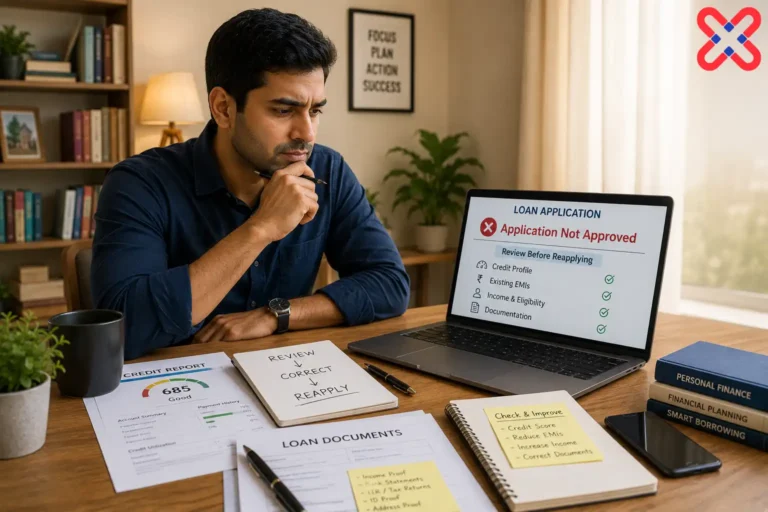
Rather than applying simultaneously to numerous lenders after a rejection, it can be useful to understand the reasons for the outcome and review the credit report first.
How Can You Strengthen Your Credit Profile?
Credit profiles generally develop over time rather than changing through a single action.
Borrowers can focus on maintaining timely repayments, keeping outstanding obligations manageable, using available credit prudently and avoiding unnecessary repeated credit applications.
It is also sensible to periodically review your credit report for inaccurate or outdated information.
RBI requires credit information companies to provide individuals access to one free full credit report, including the credit score, once in a calendar year, subject to authentication.
If information in a report appears incorrect, borrowers should use the relevant credit bureau’s dispute process rather than simply assuming the reported score is accurate.
Credit Score Is Important — But It Is Only One Part of Eligibility
A credit score can materially influence how lenders view a borrower, but loan eligibility ultimately depends on a broader assessment.
Income, existing obligations, repayment capacity, employment or business profile, loan structure, security and lender-specific policies can all affect the amount and terms available.
This distinction is important when planning a borrowing requirement.
A borrower with a strong credit score may still have limited eligibility if existing obligations are high. Equally, a borrower should not assess affordability merely from the maximum amount a lender may be willing to sanction.
Eligibility tells you what may be available. Affordability requires deciding what you can comfortably repay.
For an indicative assessment of borrowing capacity, readers can also use Magnet Capital Partners’ Loan Eligibility Calculator before evaluating suitable loan options.
Looking to Discuss an Opportunity?
Connect with Magnet Capital Partners to discuss your requirements and explore how our advisory capabilities may assist.
Disclaimer
This article forms part of Insights — The Magnet Knowledge Series and is intended solely for general informational and educational purposes. It does not constitute investment, financial, legal, tax, regulatory, real estate or other professional advice, nor does it constitute an offer, solicitation, recommendation or assurance in relation to any investment, transaction, product, service or return.
Any information, views, examples, calculations, illustrations, scenarios, projections, estimates or references to valuations, yields, returns, interest rates, financial performance, market conditions or other quantitative or qualitative measures contained in this article are general or illustrative in nature. They should not be interpreted as actual, assured, promised or indicative future outcomes. Actual circumstances and outcomes may differ materially depending upon applicable facts, assumptions, market conditions, commercial considerations, regulatory requirements and other relevant factors.
Readers should undertake their own evaluation and obtain appropriate independent professional advice before making any investment, financial, business, transaction, real estate or other decision. Information contained in this article may change over time and may not reflect subsequent developments. Magnet Capital Partners makes no representation or warranty, express or implied, regarding the accuracy, completeness or continuing relevance of the information contained herein and accepts no liability arising from reliance upon or use of this article, to the extent permitted by applicable law.
Copyright
© Magnet Capital Partners. All rights reserved.
The original editorial content, organisation, structure and presentation of Insights — The Magnet Knowledge Series are protected by applicable copyright laws. No part of this article may be reproduced, republished, distributed, transmitted, adapted or commercially used, in whole or in substantial part, without the prior written permission of Magnet Capital Partners, except as permitted by applicable law. References to third-party information, data, regulations, concepts, terminology, trademarks or other materials remain subject to the rights of their respective owners, where applicable.