FOIR: How It Affects Your Loan Eligibility
When assessing a loan application, lenders look beyond a borrower’s income. An equally important consideration is how much of that income is already committed towards existing financial obligations.
This relationship is commonly assessed through FOIR — Fixed Obligation to Income Ratio.
FOIR helps a lender understand the proportion of a borrower’s monthly income that is already committed towards fixed financial obligations. It can therefore have a significant bearing on both loan eligibility and the amount a lender may be willing to sanction.
What Is FOIR?
FOIR expresses a borrower’s fixed monthly financial obligations as a percentage of monthly income.
In simplified terms:
FOIR = Fixed Monthly Obligations ÷ Monthly Income × 100
Suppose an individual earns ₹1,00,000 per month and has qualifying fixed monthly obligations of ₹30,000.
The FOIR would be:
₹30,000 ÷ ₹1,00,000 × 100 = 30%
This means 30% of the borrower’s monthly income is already committed towards the obligations considered in the calculation.
The precise income and obligations considered can vary according to the lender, borrower profile and loan product.
Why Does FOIR Matter to Lenders?
Income alone does not reveal how much additional debt a borrower can reasonably service.
Consider two borrowers who each earn ₹1,00,000 per month.
One may have no significant existing loan commitments, while the other may already be paying several EMIs. Although their incomes are identical, their capacity to take on another EMI is clearly different.
FOIR provides lenders with a way of evaluating this distinction.
A lower level of existing obligations generally leaves more income available to service a proposed loan. Higher obligations reduce that available capacity and can consequently affect eligibility.
What Is Included in FOIR?
The obligations considered for FOIR can differ between lenders, but the assessment may include commitments such as:
- existing home-loan EMIs;
- personal-loan EMIs;
- vehicle-loan EMIs;
- business or other loan repayments;
- certain credit-card obligations; and
- other recurring financial commitments recognised by the lender.
Not every household expense is necessarily treated as a fixed obligation for this purpose.
Similarly, lenders may calculate eligible monthly income differently depending on whether an applicant is salaried, self-employed or operating a business.
For this reason, FOIR should be treated as a lender-specific credit assessment parameter, rather than a universally standardised calculation.
How Does FOIR Affect Loan Eligibility?
A lender can use its acceptable FOIR level to estimate how much room remains for an additional EMI.
Consider a simplified example.
Suppose:
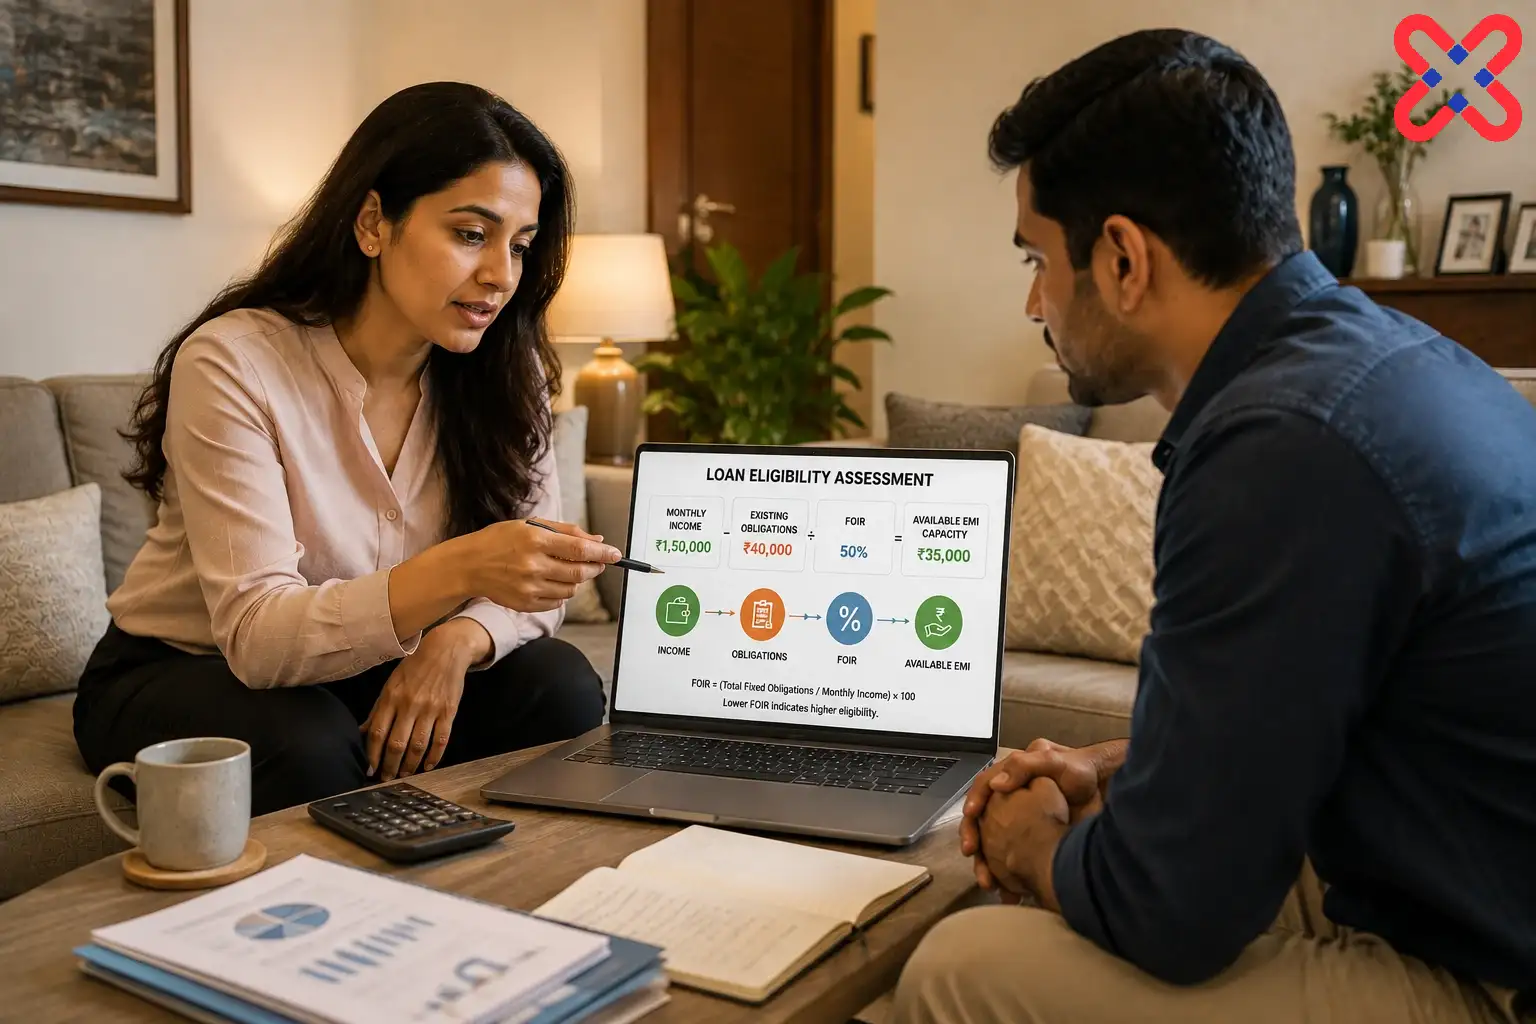
Monthly income: ₹1,50,000
Existing qualifying obligations: ₹40,000
Illustrative acceptable FOIR: 50%
At a 50% FOIR, total allowable obligations would be:
₹1,50,000 × 50% = ₹75,000
After deducting existing obligations:
₹75,000 − ₹40,000 = ₹35,000
The borrower would therefore have an indicative EMI capacity of ₹35,000 under these assumptions.
The lender can then use this EMI capacity, together with the applicable interest rate and tenure, to estimate the potential loan amount.
This explains why existing obligations can directly influence loan eligibility even when income remains unchanged.
Is There an Ideal FOIR?
There is no single FOIR percentage applicable to every borrower or every lender.
Acceptable levels can vary depending on factors such as:
- income;
- employment or business profile;
- loan product;
- credit history;
- age and remaining earning period;
- existing liabilities;
- proposed tenure; and
- lender-specific credit policy.
Accordingly, statements suggesting that every borrower must remain below one particular FOIR percentage can be misleading.
A lender may accept a particular level for one borrower profile while applying a different threshold to another.
Can Higher Income Support a Higher EMI?
Potentially, but income is only one part of the assessment.
Higher income can provide greater absolute repayment capacity. However, lenders may still consider existing obligations, stability and source of income, credit history and other underwriting parameters.
For example, a borrower earning ₹2,00,000 per month with substantial existing EMIs may have less additional borrowing capacity than another borrower with a lower income but significantly fewer obligations.
The relationship between income and commitments, rather than income alone, is therefore important.
Can Reducing Existing EMIs Improve Loan Eligibility?
Potentially, yes.
If an existing loan is fully repaid and the corresponding EMI is no longer treated as an obligation, the borrower’s available EMI capacity may increase.
Similarly, reducing other recognised fixed obligations can improve the relationship between monthly income and committed repayments.
However, borrowers should not prematurely close loans or deploy savings merely to improve an eligibility calculation without considering the financial implications.
Eligibility is only one aspect of a borrowing decision.
FOIR and Credit Score Are Not the Same
FOIR and credit score evaluate different aspects of a borrower’s financial profile.
FOIR primarily considers repayment capacity by examining income relative to existing obligations.
Credit score primarily reflects credit behaviour and credit history based on information reported to credit information companies.
A borrower can therefore have a strong credit score but limited additional eligibility because existing obligations are high.
Conversely, low existing obligations do not necessarily compensate for a weak credit history.
Lenders generally assess several parameters together rather than relying exclusively on either measure.
Eligibility Is Different From Affordability
A lender’s assessment of how much a borrower may be eligible to borrow should not automatically determine how much the borrower chooses to borrow.
A household may have future expenses, irregular income requirements, education costs, investments, dependants or other commitments that are not fully reflected in a lender’s eligibility calculation.
Borrowers should therefore consider whether the proposed EMI remains comfortable under their own financial circumstances.
Loan eligibility indicates borrowing capacity under specified assumptions. Affordability considers whether that borrowing fits comfortably within your broader finances.
For an indicative assessment, readers can use Magnet Capital Partners’ Loan Eligibility Calculator, which incorporates monthly income, existing obligations and an assumed FOIR to estimate available EMI capacity and potential loan eligibility.
Looking to Discuss an Opportunity?
Connect with Magnet Capital Partners to discuss your requirements and explore how our advisory capabilities may assist.
Disclaimer
This article forms part of Insights — The Magnet Knowledge Series and is intended solely for general informational and educational purposes. It does not constitute investment, financial, legal, tax, regulatory, real estate or other professional advice, nor does it constitute an offer, solicitation, recommendation or assurance in relation to any investment, transaction, product, service or return.
Any information, views, examples, calculations, illustrations, scenarios, projections, estimates or references to valuations, yields, returns, interest rates, financial performance, market conditions or other quantitative or qualitative measures contained in this article are general or illustrative in nature. They should not be interpreted as actual, assured, promised or indicative future outcomes. Actual circumstances and outcomes may differ materially depending upon applicable facts, assumptions, market conditions, commercial considerations, regulatory requirements and other relevant factors.
Readers should undertake their own evaluation and obtain appropriate independent professional advice before making any investment, financial, business, transaction, real estate or other decision. Information contained in this article may change over time and may not reflect subsequent developments. Magnet Capital Partners makes no representation or warranty, express or implied, regarding the accuracy, completeness or continuing relevance of the information contained herein and accepts no liability arising from reliance upon or use of this article, to the extent permitted by applicable law.
Copyright
© Magnet Capital Partners. All rights reserved.
The original editorial content, organisation, structure and presentation of Insights — The Magnet Knowledge Series are protected by applicable copyright laws. No part of this article may be reproduced, republished, distributed, transmitted, adapted or commercially used, in whole or in substantial part, without the prior written permission of Magnet Capital Partners, except as permitted by applicable law. References to third-party information, data, regulations, concepts, terminology, trademarks or other materials remain subject to the rights of their respective owners, where applicable.