Home Loan Affordability: What Really Matters
Buying a home is often one of the largest financial commitments an individual or family undertakes. The purchase decision may begin with the price of the property, but the financial implications extend well beyond the amount being borrowed.
A home loan can continue for many years, during which income, expenditure, interest rates and personal circumstances may change. Assessing affordability therefore requires more than determining whether a lender is willing to sanction a particular amount or whether the current EMI appears manageable.
The more useful question is whether the borrowing commitment can remain comfortable alongside other financial priorities over an extended period.
Affordability Is Different from Eligibility
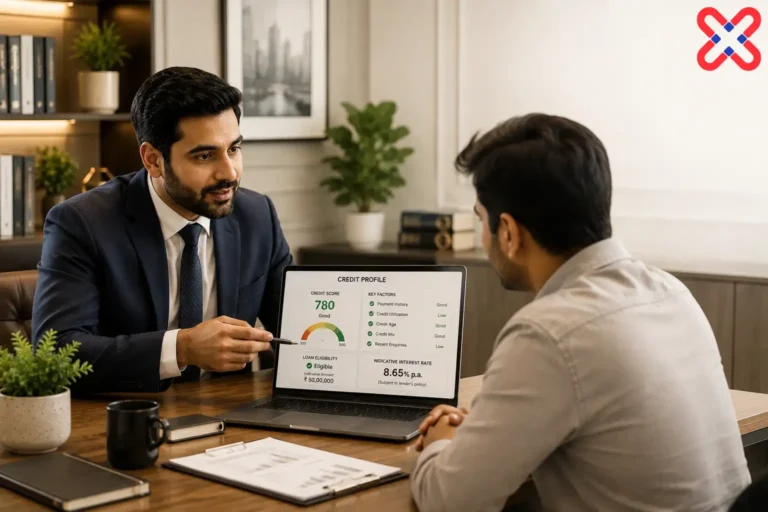
Loan eligibility and loan affordability are related, but they are not the same.
A lender may determine eligibility by considering factors such as income, existing obligations, credit profile, age, employment or business stability and the value of the property. These parameters help the lender assess the amount it may be prepared to finance.
Affordability is a broader assessment from the borrower’s perspective.
A household may technically qualify for a particular loan amount while finding the resulting repayment commitment restrictive when considered alongside regular expenditure, education costs, insurance, savings, investments and other financial responsibilities.
The maximum amount available should therefore not automatically become the amount that ought to be borrowed.
A more sustainable approach begins with the household’s own financial capacity and then considers how much borrowing can reasonably fit within it.
Looking Beyond the Property Price
The purchase price is the most visible cost of buying a home, but it is not necessarily the complete financial requirement.
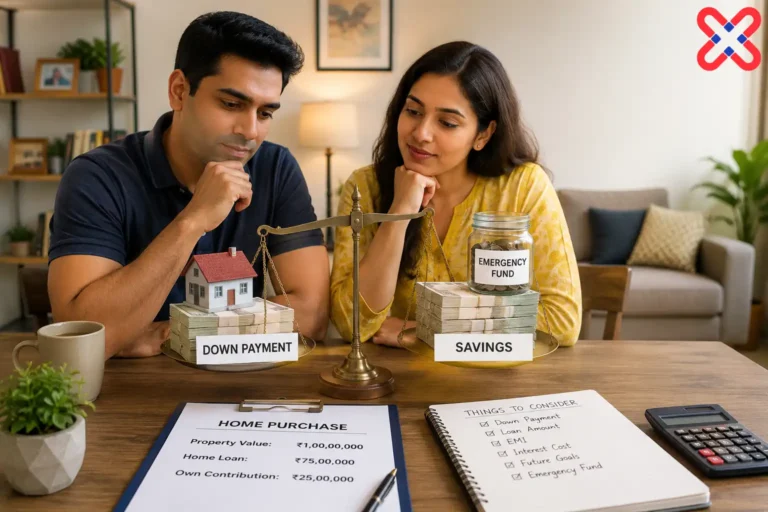
Depending upon the transaction and applicable requirements, a buyer may need to provide a portion of the property value from personal resources. There may also be registration-related expenses, applicable duties, documentation costs and other transaction expenses.
A new home can create further expenditure on interiors, furnishing, appliances, relocation or immediate improvements. These costs may individually appear manageable but can collectively require meaningful liquidity around the time of purchase.
Using a disproportionate share of available savings for the acquisition can leave the household with a valuable property but limited financial flexibility.
Home-loan planning should therefore consider both the borrowing requirement and the personal funds that will remain available after the transaction.
Assessing the EMI in the Context of Cash Flow
The EMI is central to home-loan affordability because it converts a large borrowing amount into a recurring household obligation.
Yet an EMI should not be evaluated in isolation.
A useful assessment begins with regular income and considers essential household expenditure, existing loan repayments, insurance commitments, savings requirements and reasonably foreseeable expenses. The objective is to understand what remains available after these commitments rather than simply comparing the EMI with gross income.
This distinction becomes particularly important for households whose income includes variable components such as bonuses, incentives, commissions or business earnings.
A repayment commitment built primarily around consistently available income may provide greater resilience than one that depends upon favourable variable income continuing every year.
The appropriate level will differ between borrowers. The underlying principle is that the EMI should coexist with the household’s broader financial life rather than dominate it.
Tenure Changes More Than the EMI
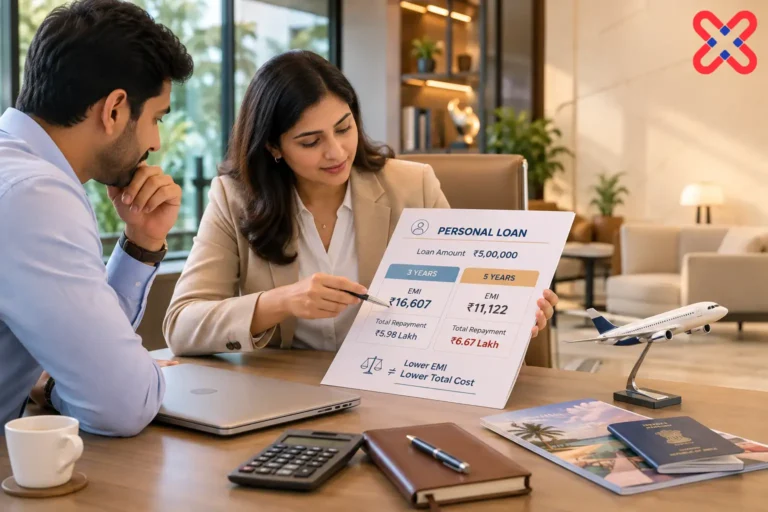
A longer loan tenure can make a home purchase appear more affordable because the principal is repaid over a greater number of instalments.
This can reduce the immediate monthly burden and may provide greater cash-flow flexibility.
However, extending the tenure also generally means that interest continues to accrue over a longer period, potentially increasing the overall amount paid during the life of the loan.
A shorter tenure creates the opposite trade-off. Monthly repayments may be higher, but the borrowing can be extinguished sooner and the cumulative interest burden may be lower, depending upon the applicable rate and loan structure.
Neither approach is automatically preferable.
The appropriate tenure depends upon income, age, financial priorities, other obligations and the degree of monthly flexibility the borrower wishes to preserve. Evaluating tenure therefore requires balancing present affordability with the longer-term cost of borrowing.
Allowing for Changes in Interest Rates
Home loans may be structured in ways that allow the applicable interest rate to change over time. Where this occurs, the cost and repayment profile of the loan can change as broader interest-rate conditions and lender-specific terms evolve.
Depending upon the loan structure, a rate change may affect the EMI, the remaining tenure or a combination of the two.
This matters because a loan that appears comfortable under prevailing conditions should ideally retain some capacity to absorb less favourable circumstances.
Borrowers need not attempt to predict future interest rates precisely. Such forecasts are inherently uncertain.
Instead, affordability can be examined under more than one repayment scenario. Considering whether household finances could accommodate some increase in the repayment burden provides a more robust perspective than assuming present conditions will remain unchanged throughout a long tenure.
Preserving Financial Flexibility
A home is an important asset, but home ownership is only one component of household finances.
Over the life of a home loan, borrowers may need resources for healthcare, education, family responsibilities, retirement planning, business requirements or periods of income disruption. Unexpected expenditure can also arise without warning.
Committing nearly all available monthly surplus to the home loan can reduce the ability to respond to these needs.
Liquidity therefore deserves attention when assessing affordability.
A larger down payment can reduce the amount borrowed and consequently the repayment burden. However, using most available liquid savings merely to minimise the loan may create a different vulnerability.
The appropriate balance between borrowing and using personal funds depends upon individual circumstances. The objective is not necessarily to minimise debt at any cost, but to structure the purchase without leaving the household financially inflexible.
Considering Existing and Future Obligations
A home loan does not exist independently of other financial commitments.
Existing vehicle loans, personal loans, education loans, credit obligations or business-related commitments can influence the amount of cash flow available for housing repayments.
Future obligations can be equally important.
A household expecting significant education expenditure, a change in employment, retirement within the loan tenure or another major financial commitment may reasonably take those factors into account before deciding how much to borrow.
Long-tenure financing inevitably involves uncertainty. It is impossible to anticipate every development over many years.
The objective is therefore not to create a perfect forecast, but to avoid assessing affordability solely on the basis of today’s income and today’s expenditure.
A reasonable margin for change can make the borrowing structure more resilient.
Prepayment and Repayment Flexibility
Financial circumstances do not always remain static after a home loan is taken.
Income may rise, savings may accumulate or a borrower may receive bonuses or other cash inflows. In such circumstances, the ability to make additional repayments can become relevant.
Prepayment can potentially reduce the outstanding principal and may reduce future interest or shorten the remaining tenure, subject to the terms applicable to the loan.
Borrowers should therefore understand the lender’s provisions concerning part-prepayment, foreclosure and related conditions before finalising a facility.
The existence of flexibility does not mean that every available surplus should automatically be used to repay the loan. Other priorities, including liquidity and alternative financial requirements, also matter.
What is valuable is having sufficient understanding of the available options so that future decisions can be made deliberately.
A Home Loan Should Remain Sustainable
The affordability of a home loan is ultimately determined over years rather than on the day it is sanctioned.
Property price, loan amount and interest rate are important, but they form only part of the assessment. Income stability, EMI capacity, tenure, liquidity, existing obligations, future expenditure and the ability to withstand changing circumstances all contribute to whether a borrowing commitment remains sustainable.
A well-considered home loan is therefore not necessarily the largest facility for which a borrower qualifies, nor simply the facility offering the lowest initial EMI.
It is one whose repayment structure fits reasonably within the borrower’s broader financial circumstances while leaving sufficient room for other priorities and uncertainties.
Approaching affordability from this wider perspective can help transform the question from “How much can I borrow?” to the more meaningful one: “How much can I comfortably sustain?”
Looking to Discuss an Opportunity?
Connect with Magnet Capital Partners to discuss your requirements and explore how our advisory capabilities may assist.
Disclaimer
This article forms part of Insights — The Magnet Knowledge Series and is intended solely for general informational and educational purposes. It does not constitute investment, financial, legal, tax, regulatory, real estate or other professional advice, nor does it constitute an offer, solicitation, recommendation or assurance in relation to any investment, transaction, product, service or return.
Any information, views, examples, calculations, illustrations, scenarios, projections, estimates or references to valuations, yields, returns, interest rates, financial performance, market conditions or other quantitative or qualitative measures contained in this article are general or illustrative in nature. They should not be interpreted as actual, assured, promised or indicative future outcomes. Actual circumstances and outcomes may differ materially depending upon applicable facts, assumptions, market conditions, commercial considerations, regulatory requirements and other relevant factors.
Readers should undertake their own evaluation and obtain appropriate independent professional advice before making any investment, financial, business, transaction, real estate or other decision. Information contained in this article may change over time and may not reflect subsequent developments. Magnet Capital Partners makes no representation or warranty, express or implied, regarding the accuracy, completeness or continuing relevance of the information contained herein and accepts no liability arising from reliance upon or use of this article, to the extent permitted by applicable law.
Copyright
© Magnet Capital Partners. All rights reserved.
The original editorial content, organisation, structure and presentation of Insights — The Magnet Knowledge Series are protected by applicable copyright laws. No part of this article may be reproduced, republished, distributed, transmitted, adapted or commercially used, in whole or in substantial part, without the prior written permission of Magnet Capital Partners, except as permitted by applicable law. References to third-party information, data, regulations, concepts, terminology, trademarks or other materials remain subject to the rights of their respective owners, where applicable.