Joint Home Loans: Benefits and Key Considerations
Buying a home is often one of the largest financial commitments a household undertakes. When the required loan is difficult to support on one person’s income, applying jointly with another eligible borrower can sometimes provide an alternative.
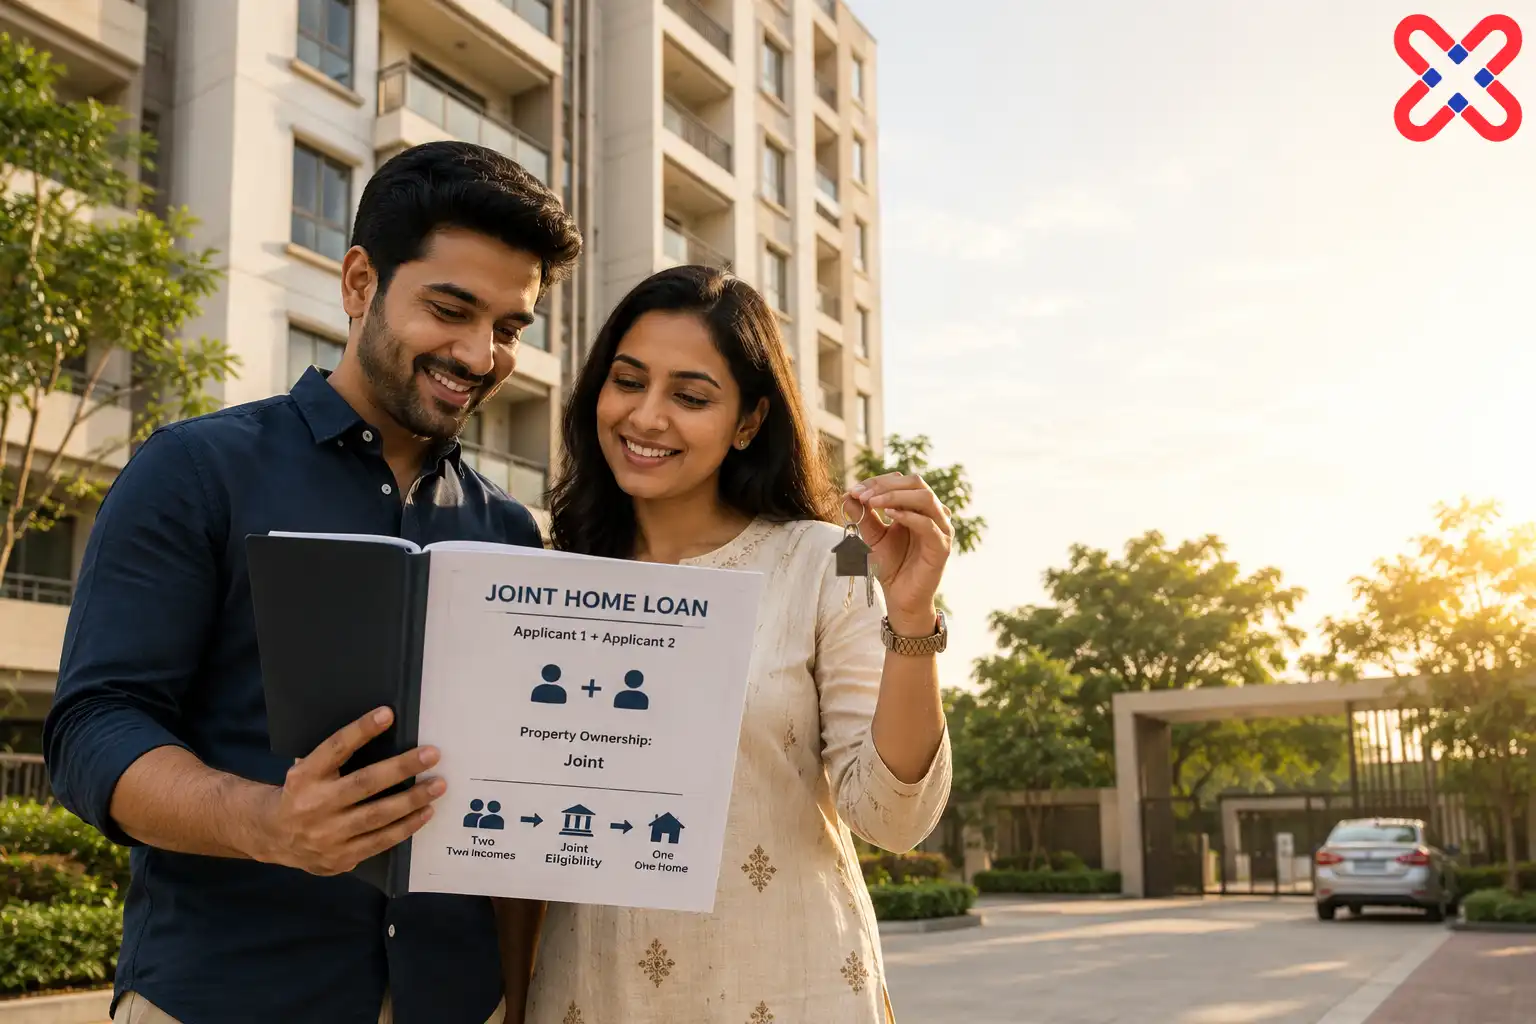
A joint home loan allows two or more applicants to borrow together for the purchase of a property. Spouses are common joint applicants, although lenders may permit other combinations of family members subject to their individual policies.
Joint borrowing can potentially improve loan eligibility and distribute repayment responsibility, but it also creates a shared financial obligation that may continue for many years. Property ownership is another important consideration, particularly where the home itself is being purchased jointly.
Understanding these aspects before applying can help borrowers structure the purchase and financing more appropriately.
What Is a Joint Home Loan?
A joint home loan has more than one borrower responsible for repayment of the same housing loan.
The lender evaluates the applicants together, although each applicant’s income, existing obligations, credit history, age and other eligibility parameters may be assessed individually.
Where the incomes of eligible co-applicants are considered by the lender, their combined repayment capacity may support a higher loan amount than either applicant could obtain independently.
However, adding another person to an application does not automatically increase eligibility. The additional applicant must also satisfy the lender’s underwriting requirements.
How Combining Income Can Improve Eligibility
Loan eligibility depends substantially on repayment capacity.
Suppose one applicant earns ₹1,00,000 per month but already has existing financial obligations. The amount of additional EMI that the lender considers affordable may consequently be limited.
If an eligible spouse with an independent and stable income joins the application, the lender may consider the combined income while assessing the household’s ability to service the proposed home loan.
This can potentially:
- increase the eligible loan amount;
- make a desired property more financially accessible;
- improve the overall repayment profile; or
- provide greater flexibility in structuring the loan.
The actual benefit depends upon the lender’s assessment of both applicants.
Property Ownership and Joint Home Loans
Property ownership is an important consideration when structuring a joint home loan.
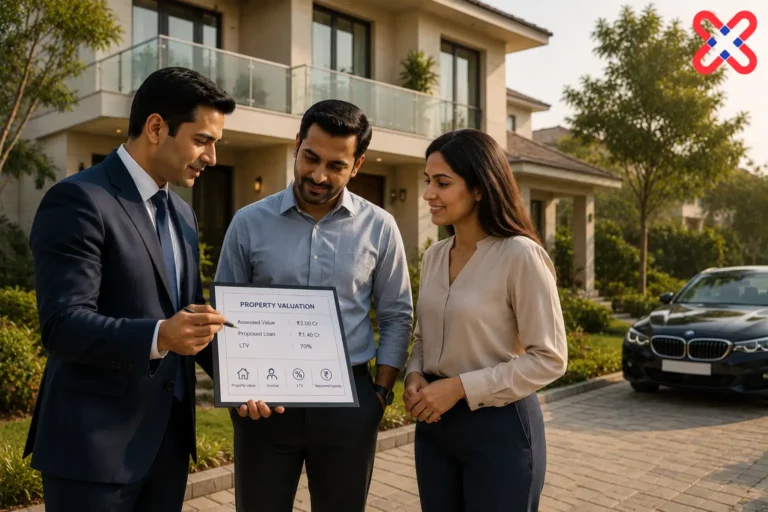
Where a property is purchased in the names of two or more individuals, lenders generally require all co-owners of the property to be co-applicants or co-borrowers on the home loan. This ensures that the persons holding ownership rights in the property are also appropriately connected with the borrowing secured against it.
However, the reverse may not always apply. Depending on the lender’s policy and the relationship between applicants, a person may sometimes be permitted to join the loan as a co-applicant without necessarily becoming a co-owner of the property.
For example, spouses purchasing and owning a home jointly would ordinarily apply for the home loan together, with both names reflected appropriately in the property and loan documentation.
Borrowers should therefore decide the intended ownership structure before finalising the loan application, rather than treating ownership and borrowing arrangements as separate decisions.
Both Borrowers Assume Repayment Responsibility
A joint home loan should not be viewed simply as a mechanism for increasing eligibility.
It creates a joint financial commitment.
Even where the borrowers have privately decided how the EMI will be divided between them, their responsibilities towards the lender are governed by the loan documentation.
If one borrower stops contributing towards the EMI because of unemployment, financial difficulty or another circumstance, the repayment obligation does not simply disappear.
Both applicants should therefore understand the extent of their obligations before signing the loan documents.
Credit Profiles of Both Applicants Matter
Joint applications bring more than one financial profile into the lender’s assessment.
A co-applicant with stable income and a strong repayment history may strengthen the overall application. Conversely, an applicant with significant existing debt or adverse credit history may not necessarily improve eligibility and could affect the lender’s assessment.
Before applying jointly, it can therefore be useful for both applicants to review their:
- credit histories;
- existing EMIs;
- outstanding loans;
- income stability; and
- other significant financial commitments.
The objective should be to create a financially sustainable borrowing structure rather than merely adding another applicant to increase the amount sought.
Age Can Influence the Loan Structure
Age can become particularly relevant when joint applicants are at different stages of their working lives.
Home loans can have long repayment periods. A lender may consider the age of applicants while determining the permissible tenure, particularly where repayment extends towards retirement.
For example, adding an older earning family member does not necessarily mean that the lender will simply combine the income and retain the longest possible tenure.
The lender’s policy regarding age, income continuity and retirement can affect the eventual loan structure.
Should Both Borrowers Contribute Equally?
Not necessarily.
Two borrowers may have very different incomes. One may therefore contribute a larger proportion of the EMI than the other.
The appropriate arrangement depends upon the household’s finances and the understanding between the borrowers.
What matters is that both applicants understand how the EMI will be funded and whether the arrangement remains manageable if circumstances change.
A couple may also choose to maintain sufficient liquidity so that a temporary disruption to one person’s income does not immediately place the home-loan repayment under pressure.
Consider Future Borrowing Capacity
A joint home loan can also affect future financial flexibility.
Because both individuals are borrowers, the outstanding home-loan obligation may be considered when either subsequently applies for another loan.
This could influence future eligibility for a:
- car loan;
- personal loan;
- business loan;
- loan against property; or
- another housing loan.
Borrowers should therefore consider not only whether they qualify for the joint home loan today, but also how the obligation may interact with their future borrowing requirements.
What Happens if One Borrower’s Income Changes?
A home loan may continue for 15, 20 or even more years. Household circumstances can change substantially over such a period.
One borrower may change employment, take a career break, start a business, retire or experience an interruption in income.
Before deciding how much to borrow jointly, it can therefore be useful to ask a simple question:
Could the household continue servicing the EMI if one income temporarily reduced or stopped?
The answer can provide a more realistic measure of affordability than simply borrowing the maximum amount for which the applicants qualify.
Joint Eligibility Should Not Determine the Property Budget
A higher eligible loan amount can expand the range of properties available to a buyer.
But higher eligibility does not necessarily mean that the household should borrow more.
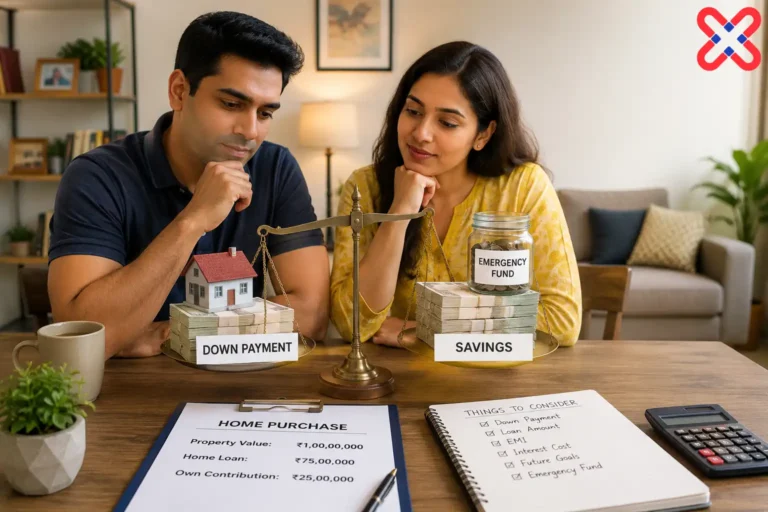
The EMI must coexist with other requirements such as living expenses, children’s education, insurance, emergency reserves, investments and retirement planning.
Borrowers should therefore distinguish between:
what the lender may be willing to lend and what the household can comfortably repay.
That distinction becomes especially important when two incomes significantly increase the sanctioned amount.
Documentation for a Joint Application
Both applicants will generally need to provide the documents required by the lender for their respective profiles.
Depending upon the applicants and lender, these may include identity and address documents, income records, bank statements, employment or business information and details of existing financial obligations.
Property-related documentation will also be required as part of the home-loan process.
Where the property is jointly owned, the ownership documentation and loan documentation should appropriately reflect the parties involved.
Keeping the financial and property information organised and consistent can help make the assessment process more efficient.
Is a Joint Home Loan Always Better?
No.
A joint home loan can be useful where combining eligible incomes improves repayment capacity or where the property and financial commitment are genuinely intended to be shared.
But there may be little reason to add another borrower where one applicant independently qualifies comfortably for the required amount and joint borrowing provides no meaningful financial or practical advantage.
Similarly, a person should not be added to a long-term borrowing arrangement merely to increase eligibility without considering the resulting repayment responsibilities and implications for future borrowing.
The decision should arise from the household’s actual financial and ownership circumstances.
Making the Decision Together
A joint home loan can help households combine their financial strength when purchasing a home. Its advantages, however, come with equally important shared responsibilities.
Before applying, borrowers should consider property ownership, income, eligibility, credit profiles, EMI contribution, loan tenure, future borrowing requirements and the ability to manage repayment if circumstances change.
Where the property is being purchased jointly, the ownership structure and financing structure should also be considered together from the outset.
The objective should not simply be to maximise the home loan available.
A well-structured joint home loan should enable the borrowers to purchase the home they want while keeping the ownership arrangement clear and the resulting financial commitment sustainable over the long term.
Looking to Discuss an Opportunity?
Connect with Magnet Capital Partners to discuss your requirements and explore how our advisory capabilities may assist.
Disclaimer
This article forms part of Insights — The Magnet Knowledge Series and is intended solely for general informational and educational purposes. It does not constitute investment, financial, legal, tax, regulatory, real estate or other professional advice, nor does it constitute an offer, solicitation, recommendation or assurance in relation to any investment, transaction, product, service or return.
Any information, views, examples, calculations, illustrations, scenarios, projections, estimates or references to valuations, yields, returns, interest rates, financial performance, market conditions or other quantitative or qualitative measures contained in this article are general or illustrative in nature. They should not be interpreted as actual, assured, promised or indicative future outcomes. Actual circumstances and outcomes may differ materially depending upon applicable facts, assumptions, market conditions, commercial considerations, regulatory requirements and other relevant factors.
Readers should undertake their own evaluation and obtain appropriate independent professional advice before making any investment, financial, business, transaction, real estate or other decision. Information contained in this article may change over time and may not reflect subsequent developments. Magnet Capital Partners makes no representation or warranty, express or implied, regarding the accuracy, completeness or continuing relevance of the information contained herein and accepts no liability arising from reliance upon or use of this article, to the extent permitted by applicable law.
Copyright
© Magnet Capital Partners. All rights reserved.
The original editorial content, organisation, structure and presentation of Insights — The Magnet Knowledge Series are protected by applicable copyright laws. No part of this article may be reproduced, republished, distributed, transmitted, adapted or commercially used, in whole or in substantial part, without the prior written permission of Magnet Capital Partners, except as permitted by applicable law. References to third-party information, data, regulations, concepts, terminology, trademarks or other materials remain subject to the rights of their respective owners, where applicable.