Home Loan Down Payment: How Much Is Enough?
Buying a home generally requires the buyer to contribute a portion of the property cost from personal funds, while the balance may be financed through a home loan.
This upfront contribution is commonly referred to as the down payment.
A larger down payment reduces the amount that needs to be borrowed. That sounds inherently beneficial, but using substantially more savings towards the property can also reduce the liquidity available for other expenses and financial goals.
The appropriate down payment is therefore not simply the largest amount a buyer can arrange. It requires balancing lower borrowing with adequate financial flexibility.
What Is a Home Loan Down Payment?
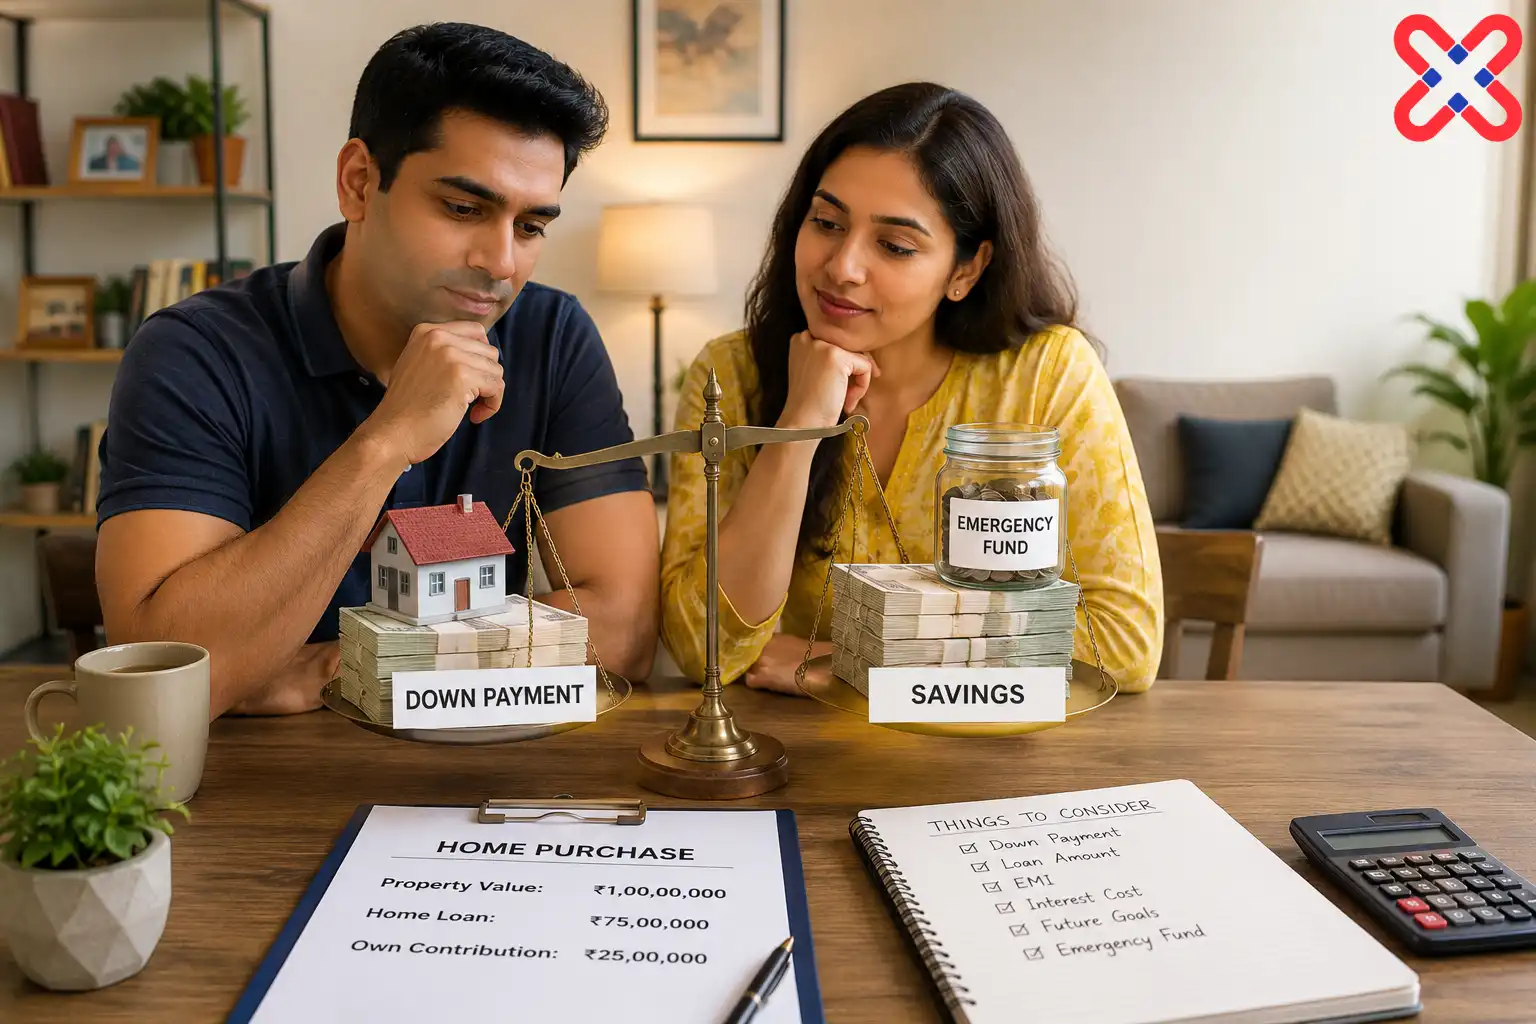
Suppose a property costs ₹1 crore and a lender finances ₹75 lakh.
The remaining ₹25 lakh must ordinarily be arranged by the buyer from eligible own sources. In simplified terms, this represents the buyer’s contribution towards the purchase.
The actual amount that needs to be contributed can depend on factors including:
- property value;
- amount considered by the lender;
- permissible loan-to-value ratio;
- borrower’s eligibility;
- lender policy; and
- nature of the property and transaction.
The buyer may also need funds for expenses that are not financed as part of the home loan.
Understanding Loan-to-Value Ratio
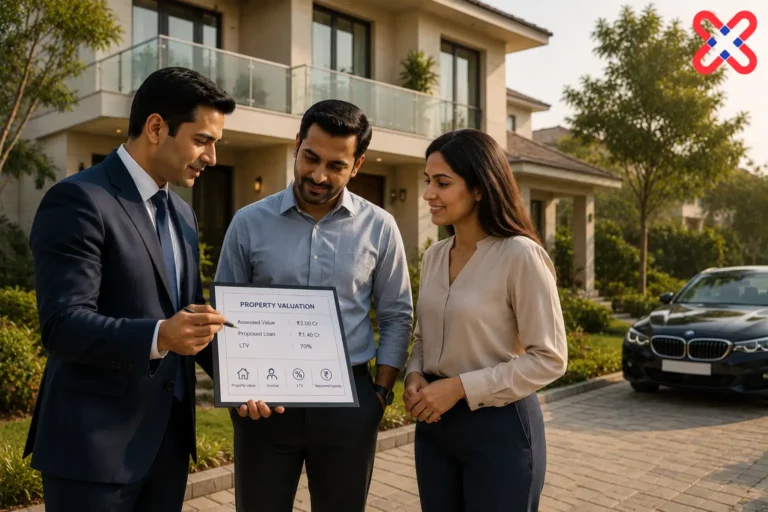
The Loan-to-Value ratio, or LTV, broadly measures the loan amount relative to the value of the property considered for lending purposes.
For example, if a property considered at ₹80 lakh is financed with a ₹60 lakh home loan:
LTV = ₹60 lakh ÷ ₹80 lakh = 75%
The remaining portion must be funded by the buyer, apart from other applicable transaction expenses.
LTV limits applicable to housing loans are influenced by regulatory requirements as well as individual lender policies. Buyers should therefore confirm the amount a lender is prepared to finance rather than assuming that a fixed percentage will always be available.
A Larger Down Payment Means a Smaller Loan
The most immediate advantage of making a larger down payment is straightforward: you borrow less.
Consider a property costing ₹1 crore.
If the buyer contributes ₹20 lakh and borrows ₹80 lakh, the EMI and future interest are calculated on the larger loan.
If the buyer instead contributes ₹35 lakh and borrows ₹65 lakh, the principal on which interest accrues is substantially lower.
Assuming the same interest rate and tenure, the smaller loan would generally result in:
- a lower EMI;
- lower aggregate interest outgo; or
- greater flexibility to choose a shorter tenure.
This can make the housing loan easier to service over the long term.
But More Down Payment Is Not Automatically Better
There is another side to the decision.
A buyer may have ₹40 lakh available in savings and conclude that the entire amount should be used towards the property simply because doing so reduces the loan.
That could leave very little liquid money after the purchase.
A home purchase can involve expenses beyond the amount shown as the property price. Depending on the transaction, buyers may need to provide separately for registration-related costs, moving expenses, interiors, furniture, repairs or other requirements.
Using nearly all available savings for the down payment can therefore create a situation in which the borrower owns a valuable asset but has insufficient readily accessible funds.
Preserve an Emergency Reserve
A long-term home loan assumes that future EMIs will continue to be paid regularly.
Yet income and expenses can change.
A job transition, temporary interruption in earnings, medical expense, family requirement or unexpected repair can affect household cash flow.
Before allocating additional savings towards the down payment, buyers should therefore consider retaining an appropriate emergency reserve.
The exact amount depends on individual circumstances, but the principle is important:
The home purchase should not leave the household financially fragile immediately after the transaction.
Consider the EMI You Are Comfortable Paying
The down-payment decision and EMI decision should be considered together.
A smaller down payment means a larger home loan, which generally means a higher EMI for the same tenure and interest rate.
A larger down payment can bring that EMI down.
Instead of starting with the question, “What is the minimum down payment?”, a buyer can therefore approach the decision from the opposite direction:
What EMI can I comfortably service every month?
Once a comfortable EMI range is identified, the corresponding loan requirement and down payment become easier to evaluate.
Eligibility and Affordability Are Different
A lender may determine that a borrower qualifies for a particular home-loan amount based on income, existing obligations, credit profile, tenure and other parameters.
That does not necessarily mean the borrower should take the entire eligible amount.
Eligibility represents what a lender may be prepared to finance.
Affordability represents what the borrower can comfortably repay while continuing to meet other financial commitments.
A higher down payment can reduce the EMI to a more comfortable level even when the borrower technically qualifies for a larger loan.
Don’t Forget Other Purchase Costs
The property price is not always the buyer’s complete cash requirement.
Depending on the property and transaction, additional expenditure may arise towards matters such as stamp duty, registration and other applicable transaction or possession-related costs.
There may also be practical expenditure after purchase, including:
- interiors;
- furniture and appliances;
- shifting;
- repairs or modifications;
- maintenance deposits; and
- other household setup costs.
Buyers should therefore estimate the total cash requirement surrounding the purchase, rather than allocating all available funds solely between the property price and home loan.
Should You Invest the Money Instead?
Some buyers may consider making a smaller down payment and retaining additional funds for investment.
This creates a different financial comparison.
Reducing the home loan produces a relatively identifiable benefit through lower borrowing and avoided future interest. Investment returns, on the other hand, depend on the chosen asset, time horizon and associated risk.
It is therefore inappropriate to assume that investing will necessarily produce a return greater than the home-loan cost.
The decision should consider the buyer’s risk tolerance, liquidity requirements, investment horizon and overall financial plan.
A Down Payment Should Not Depend on Borrowed Money
The purpose of the buyer’s contribution is to demonstrate genuine participation in funding the property purchase.
Using another expensive borrowing merely to arrange the home-loan down payment can increase the household’s overall debt burden.
For example, funding the contribution through a personal loan could create an additional EMI precisely when the borrower is taking on a substantial home-loan obligation.
It may also affect the borrower’s overall repayment capacity.
Buyers should therefore evaluate the combined burden of all borrowings, not merely the home-loan EMI in isolation.
What if You Have More Savings Later?
Choosing not to put every available rupee into the initial down payment does not necessarily mean the borrower must retain the larger loan throughout its entire tenure.
If surplus funds become available later, the borrower may consider making a part-prepayment, subject to the applicable loan terms.
A prepayment can reduce the outstanding principal and potentially reduce future interest.
This creates useful flexibility: the buyer can preserve adequate liquidity at the time of purchase and reconsider additional debt reduction later when the household’s financial position is clearer.
Finding the Right Balance
There is no universal down-payment percentage that is ideal for every home buyer.
The appropriate contribution depends on the interaction between:
Property Cost → Available Savings → Loan Requirement → EMI → Remaining Liquidity
A buyer with substantial savings and stable income may prefer a larger contribution to reduce long-term borrowing.
Another buyer may reasonably make a lower contribution within permissible financing limits in order to retain funds for emergencies and other near-term requirements.
Neither approach is automatically superior.
Before Finalising Your Down Payment
Before committing the amount, it can be useful to evaluate four questions:
1. How much will I need to borrow?
Understand the resulting loan amount after the proposed contribution.
2. What EMI will that create?
Evaluate whether the EMI remains comfortable alongside existing commitments.
3. How much liquid money will remain?
Allow for emergencies and expenses surrounding the home purchase.
4. Am I using too much—or too little—of my available savings?
Compare the benefit of lower borrowing with the value of retaining financial flexibility.
More Than the Minimum
The minimum contribution required for obtaining a home loan and the appropriate contribution for a particular household are not necessarily the same amount.
Making a larger down payment can reduce the loan, EMI and future interest burden. But committing excessive savings can weaken liquidity at precisely the time a household is taking on a major long-term obligation.
The objective should therefore be to find a balance: enough contribution to keep the home loan comfortable, while retaining enough financial capacity to manage life beyond the home purchase.
Looking to Discuss an Opportunity?
Connect with Magnet Capital Partners to discuss your requirements and explore how our advisory capabilities may assist.
Disclaimer
This article forms part of Insights — The Magnet Knowledge Series and is intended solely for general informational and educational purposes. It does not constitute investment, financial, legal, tax, regulatory, real estate or other professional advice, nor does it constitute an offer, solicitation, recommendation or assurance in relation to any investment, transaction, product, service or return.
Any information, views, examples, calculations, illustrations, scenarios, projections, estimates or references to valuations, yields, returns, interest rates, financial performance, market conditions or other quantitative or qualitative measures contained in this article are general or illustrative in nature. They should not be interpreted as actual, assured, promised or indicative future outcomes. Actual circumstances and outcomes may differ materially depending upon applicable facts, assumptions, market conditions, commercial considerations, regulatory requirements and other relevant factors.
Readers should undertake their own evaluation and obtain appropriate independent professional advice before making any investment, financial, business, transaction, real estate or other decision. Information contained in this article may change over time and may not reflect subsequent developments. Magnet Capital Partners makes no representation or warranty, express or implied, regarding the accuracy, completeness or continuing relevance of the information contained herein and accepts no liability arising from reliance upon or use of this article, to the extent permitted by applicable law.
Copyright
© Magnet Capital Partners. All rights reserved.
The original editorial content, organisation, structure and presentation of Insights — The Magnet Knowledge Series are protected by applicable copyright laws. No part of this article may be reproduced, republished, distributed, transmitted, adapted or commercially used, in whole or in substantial part, without the prior written permission of Magnet Capital Partners, except as permitted by applicable law. References to third-party information, data, regulations, concepts, terminology, trademarks or other materials remain subject to the rights of their respective owners, where applicable.