Loan Against Property: Key Considerations
Owning a property can create access to capital without requiring the owner to sell the asset.
A Loan Against Property (LAP) allows an eligible borrower to raise funds by offering an acceptable property as security to a lender. The borrower continues to own the property and, subject to the terms of the financing, ordinarily continues to use it while repaying the loan.
For a business owner, professional or individual requiring a substantial amount of funding, a LAP can potentially provide access to a larger loan and longer repayment tenure than many unsecured borrowing alternatives.
But the existence of a valuable property does not automatically make borrowing against it appropriate—or determine how much a lender will provide.
A sound LAP decision requires consideration of property value, loan-to-value ratio, income, cash flow, end-use, interest rate, tenure, repayment capacity and the consequences of offering an important asset as security.
What Is a Loan Against Property?
A Loan Against Property is a secured loan in which an eligible property is mortgaged or otherwise charged in favour of the lender as security for the borrowing.
Depending upon the lender’s policy and the property, acceptable security may include certain:
- residential properties;
- commercial properties;
- industrial properties; and
- other eligible real estate.
Residential and commercial properties are commonly accepted for LAP, although eligibility and terms vary by lender.
The borrower receives the sanctioned funding but does not sell the property to the lender. Ownership ordinarily remains with the borrower, subject to the security created in favour of the lender.
Once the loan and applicable obligations are fully discharged, the lender’s security is released in accordance with the financing documents and applicable process.
Why Do Borrowers Use a LAP?
A LAP can be considered for a variety of legitimate funding requirements, subject to lender policy and applicable regulations.
For example, a business owner may own a residential or commercial property but require capital to:
- expand a business;
- purchase machinery or equipment;
- augment working capital;
- consolidate eligible debt;
- meet substantial personal expenditure;
- fund education;
- undertake property improvement; or
- address another permitted financial requirement.
The underlying principle is straightforward:
An existing real estate asset is used to support access to liquidity without an outright sale of that asset.
However, converting property value into borrowing creates a corresponding repayment obligation. Liquidity should therefore not be confused with additional wealth.
Property Value Does Not Equal Loan Amount
This is one of the most important concepts for a prospective borrower.
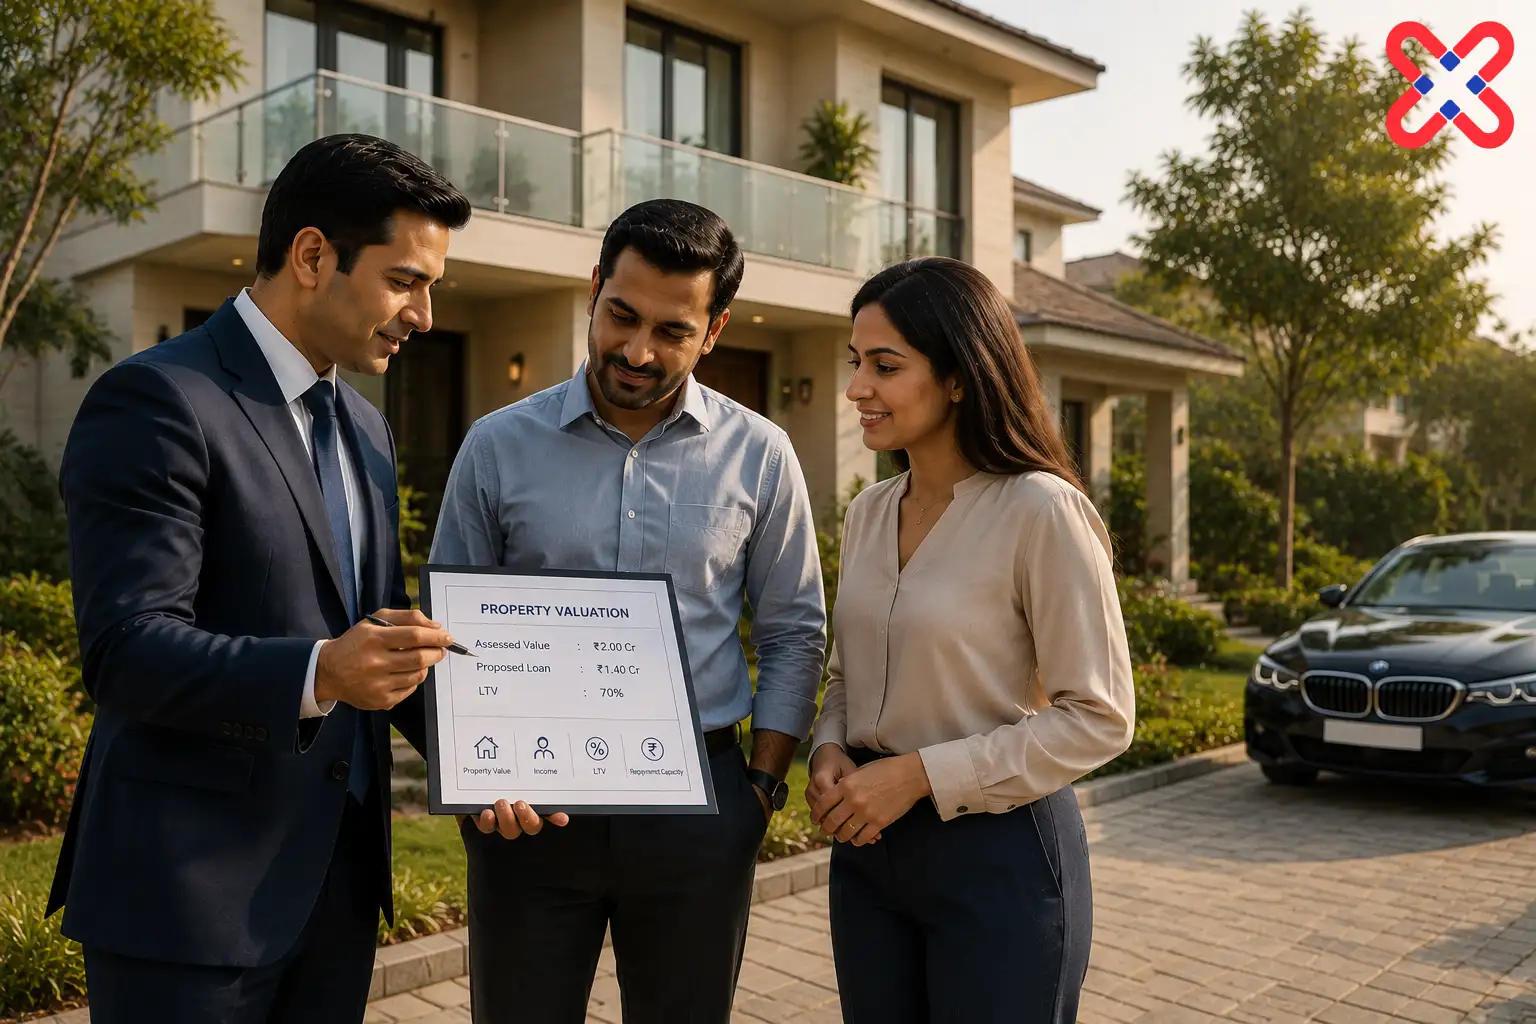
Suppose an individual owns an eligible residential property worth:
₹2 crore
It would be incorrect to assume that the borrower can obtain a ₹2 crore LAP.
Lenders generally finance only a proportion of the property’s assessed value. This relationship is commonly expressed through the Loan-to-Value ratio (LTV).
In simplified terms:
LTV = Loan Amount ÷ Property Value × 100
Suppose, purely for illustration, that a lender is willing to consider an LTV of 70% for the particular eligible residential property and borrower.
For a property valued at ₹2 crore:
₹2 crore × 70% = ₹1.40 crore
The theoretical property-value-supported amount would therefore be ₹1.40 crore.
This does not mean that every residential LAP is available at 70%, nor that ₹1.40 crore will necessarily be sanctioned. Actual LTV can vary according to the lender, property type and value, borrower profile, marketability and applicable credit policy. Published market material also illustrates that residential collateral can attract higher LTV than commercial collateral.
And even where the property supports a particular amount, the lender must still assess whether the borrower can repay it.
Two Tests: Security and Repayment Capacity
A useful way to understand LAP underwriting is to think of two separate questions.
1. Is there sufficient acceptable property security?
The lender considers matters such as property valuation, title, marketability and permissible LTV.
2. Can the borrower service the proposed debt?
The lender considers income, business cash flows, existing obligations, credit history and other underwriting parameters.
The final loan amount can therefore be constrained by either side of the equation.
Consider a borrower with a residential property valued at:
₹3 crore
At an illustrative 70% LTV, the property could theoretically support:
₹2.10 crore
But suppose the borrower’s demonstrated income and existing obligations support only ₹1.25 crore under the lender’s repayment assessment.
The lender may restrict the sanction accordingly despite the property supporting a substantially larger amount on an illustrative LTV basis.
Collateral supports the loan. It does not replace repayment capacity.
A Practical Business Expansion Example
Consider a business owner who owns an eligible residential property valued at approximately:
₹2 crore
The business requires:
₹70 lakh
for expansion, including new equipment, additional inventory and working capital.
Assume, purely for illustration, that the lender is willing to consider an LTV of 70% for that property and borrower.
The property-value-supported amount would theoretically be:
₹2 crore × 70% = ₹1.40 crore
The actual requirement of ₹70 lakh is therefore comfortably below the illustrative property-value ceiling.
But this is precisely where borrowing discipline becomes important.
The fact that the property might support ₹1.40 crore does not mean the borrower should take ₹1.40 crore.
If the genuine requirement is ₹70 lakh, borrowing another ₹70 lakh merely because additional eligibility exists would mean paying interest on capital that may not actually be required.
The lender would also still examine the business owner’s:
- income;
- profitability;
- banking conduct;
- existing debt;
- repayment history;
- cash flows;
- credit profile; and
- ability to service the proposed EMI.
If the demonstrated repayment capacity supports only ₹50 lakh, the ₹2 crore property does not automatically bridge the remaining ₹20 lakh requirement.
Maximum eligibility and appropriate borrowing are two different things.
How Is the Property Valued?
The borrower’s perception of property value and the lender’s valuation need not be identical.
A property owner may say:
“Similar properties here are being quoted at ₹2.50 crore.”
The lender’s approved valuer may arrive at:
₹2.10 crore.
Why might there be a difference?
Because asking price, expected selling price and independently assessed value are not necessarily the same.
A lender’s valuation process may consider:
- location;
- property type;
- size;
- age and condition;
- comparable transactions;
- prevailing market values;
- marketability;
- access;
- occupancy;
- approved use;
- construction and approvals; and
- other property-specific factors.
For lending purposes, the value adopted by the lender under its policies is what ultimately matters for the LTV calculation.
Marketability Matters Alongside Value
Consider two properties, each apparently worth ₹1.50 crore.
Property A is a standard apartment in an established residential locality with regular transactions involving comparable units.
Property B is an unusual commercial property with a specialised configuration and relatively few potential buyers.
Even if both receive similar headline valuations, a lender may view their marketability differently.
This matters because collateral is not assessed merely as an accounting number. The lender is also concerned with the enforceability and realisable character of its security in an adverse scenario.
Residential and Commercial Properties May Be Treated Differently
Not all properties carry the same collateral characteristics.
A self-occupied residential property, rented residential property, office, retail shop and industrial property can present different risks and marketability.
Published industry research has historically shown higher typical LTVs for self-occupied residential collateral than commercial property, while individual lender products can impose their own limits. For example, SBI currently describes one business asset-backed LAP product as financing up to 65% of the realisable value of immovable property.
A borrower should therefore avoid assuming that a percentage available against one property category—or from one lender—will automatically apply to another.
The relevant question is:
What LTV is the particular lender willing to consider for this borrower and this property?
Clear Property Title Is Important
A valuable property may still be unsuitable as collateral if there are material title or documentation problems.
Depending upon the property and lender, scrutiny may include matters such as:
- ownership documents;
- chain of title;
- existing mortgages or charges;
- approved plans;
- completion or occupancy documentation, where applicable;
- property tax records;
- society or authority documentation, where relevant; and
- other legal or technical records.
Suppose a borrower owns a property with an estimated market value of ₹4 crore but there is an unresolved ownership dispute involving another claimant.
The high market value does not eliminate the legal issue.
A lender generally needs security over which the borrower’s rights are sufficiently established and acceptable under its legal and credit policies.
Income Assessment for Salaried Borrowers
For a salaried borrower, a lender may evaluate:
- monthly income;
- employment stability;
- employer profile;
- existing EMIs;
- credit history;
- age;
- remaining working years; and
- other financial obligations.
Suppose an individual earns ₹2 lakh per month but already services EMIs of ₹90,000.
A proposed LAP requiring another substantial monthly payment may place considerably greater pressure on disposable income than the salary figure alone suggests.
The lender therefore evaluates not simply:
“How much does the borrower earn?”
but:
“How much sustainable repayment capacity remains after existing obligations?”
Income Assessment for Business Owners
Assessment can be more nuanced for self-employed borrowers and business owners.
A lender may consider:
- financial statements;
- profitability;
- cash accruals;
- banking transactions;
- turnover;
- existing borrowings;
- debt-service obligations;
- tax returns;
- business vintage;
- industry characteristics; and
- consistency of financial performance.
A business reporting high turnover does not necessarily possess strong repayment capacity.
For example:
Business A: ₹10 crore turnover and ₹30 lakh annual profit.
Business B: ₹6 crore turnover and ₹60 lakh annual profit.
Turnover alone would make Business A appear larger, but Business B may have stronger earnings relative to its size.
The broader financial picture matters.
EMI Is Not the Same as Affordability
Borrowers often begin with the question:
“What will my EMI be?”
That is important, but incomplete.
Suppose a borrower takes a hypothetical:
₹50 lakh LAP
at an illustrative interest rate of:
10% per annum
Over 10 years, the EMI would be approximately:
₹66,000 per month
Total repayments would be approximately:
₹79.3 lakh
and the approximate interest outflow:
₹29.3 lakh
Over 15 years, the EMI would fall to approximately:
₹53,700 per month
but total repayments would increase to approximately:
₹96.7 lakh
and approximate interest outflow to:
₹46.7 lakh
The longer tenure reduces monthly pressure by roughly ₹12,000 but substantially increases the total illustrative interest outflow.
This demonstrates an important principle:
Lower EMI does not necessarily mean lower cost.
Figures are rounded illustrations and exclude fees, taxes, rate changes and other charges.
Interest Rate Matters—But So Does Tenure
Borrowers naturally compare interest rates, and even a relatively small difference can matter on a large loan.
However, comparing LAP offers only on the headline interest rate can be misleading.
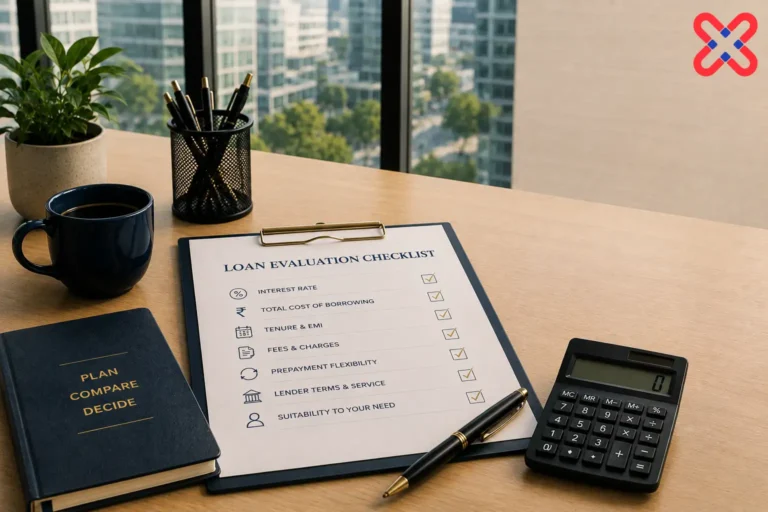
Other considerations may include:
- fixed versus floating rate structure;
- benchmark and spread;
- reset mechanism;
- processing fee;
- legal and technical charges;
- insurance, where applicable;
- documentation costs;
- prepayment conditions;
- foreclosure provisions;
- tenure; and
- other contractual terms.
A slightly lower rate accompanied by materially different charges or conditions may not necessarily produce the best overall outcome.
Fixed and Floating Rates
Depending upon the lender and product, a LAP may carry a fixed, floating or other permitted interest-rate structure.
Under a floating-rate structure, the applicable rate may change over the life of the loan based on the relevant benchmark and contractual terms.
Suppose a ₹75 lakh loan is initially priced at 9.5%.
If the applicable rate subsequently increases, the lender may—depending upon the loan terms—adjust:
- EMI;
- tenure; or
- a combination of both.
A borrower should therefore evaluate whether repayment capacity remains comfortable under a reasonable adverse interest-rate scenario rather than assessing affordability only at the initial rate.
The Purpose of Borrowing Matters
Using a property to raise capital does not by itself make the use of that capital economically sensible.
Consider two borrowers.
Borrower A raises ₹50 lakh against property to expand a profitable business with demonstrated cash flows and a clearly evaluated capital requirement.
Borrower B raises ₹50 lakh primarily to fund recurring lifestyle expenditure without a corresponding source of future cash generation.
Both borrowers may own adequate collateral.
But the economic rationale and repayment risks are very different.
The question should therefore extend beyond:
“Can I obtain this loan?”
to:
“Why am I borrowing, and how will the loan ultimately be serviced?”
LAP Versus an Unsecured Business Loan
A business owner requiring capital may sometimes have a choice between secured and unsecured borrowing.
Consider an illustrative requirement of:
₹40 lakh
An unsecured business loan may offer advantages such as:
- no property mortgage;
- potentially quicker processing in suitable cases; and
- no direct property collateral.
But it may also involve:
- higher borrowing cost;
- shorter tenure;
- smaller eligible amount; or
- higher EMI.
A LAP may potentially offer:
- larger funding capacity;
- longer tenure; and
- a lower rate than certain unsecured alternatives,
but requires acceptable property security and typically involves property-related legal and technical assessment.
The correct comparison is therefore not simply:
secured = good or unsecured = bad.
It depends upon the borrower’s requirement, cost, tenure, available security, cash flows and risk tolerance.
A Lower Rate Can Still Cost More
Suppose a borrower has two hypothetical choices for ₹30 lakh:
Option A: 11% for 5 years
Option B: 9.5% for 10 years
Option B has the lower interest rate and lower monthly EMI.
But because the money remains outstanding for much longer, its total interest cost can be greater.
This illustrates why borrowers should compare:
Interest Rate + EMI + Tenure + Total Repayment
rather than interest rate in isolation.
Using LAP for Debt Consolidation
A borrower with several higher-cost eligible debts may consider consolidating them through a LAP.
For example, suppose a business owner has:
- ₹15 lakh business borrowing;
- ₹10 lakh personal borrowing; and
- ₹5 lakh of another eligible obligation.
Consolidating ₹30 lakh into one appropriately structured secured facility could potentially simplify repayments or reduce financing cost.
But there is an important trade-off.
Previously unsecured obligations may effectively become borrowing secured against a valuable property.
The borrower should therefore assess whether the cost benefit justifies placing the property at risk.
Cheaper debt is not automatically safer debt.
Over-Borrowing Because Collateral Is Available
One of the greatest behavioural risks in secured borrowing is borrowing more simply because the lender is willing to provide it.
Return to our earlier example:
Property value: ₹2 crore
Illustrative 70% LTV ceiling: ₹1.40 crore
Actual requirement: ₹70 lakh
The additional theoretical ₹70 lakh of property-supported borrowing capacity is not a financial benefit merely because it exists.
Borrowing it would mean:
- paying interest on additional capital;
- increasing monthly obligations;
- increasing the debt secured against the property; and
- potentially using funds for purposes that were never part of the original requirement.
The appropriate loan amount should ordinarily be driven by the funding requirement and sustainable repayment capacity, not maximum eligibility.
The Property Remains Exposed to Repayment Risk
This is the fundamental distinction between LAP and unsecured borrowing.
The property is security for the loan.
If the borrower experiences financial difficulty and persistently fails to meet contractual repayment obligations, the lender may have enforcement rights over the secured property, subject to the financing documents and applicable law.
This risk deserves particular attention where the security is:
- the family’s principal residence;
- a strategically important business property;
- a long-held family asset; or
- an asset whose loss would have consequences beyond its monetary value.
A borrower should therefore not assess LAP purely through the lens of obtaining cheaper or larger funding.
The decision involves placing a real asset behind a financial obligation.
When Can a LAP Make Sense?
Subject to individual circumstances, a LAP may merit consideration where:
- a substantial legitimate funding requirement exists;
- the borrower owns suitable property;
- repayment cash flows are demonstrable;
- longer tenure is useful;
- secured borrowing economics are attractive relative to alternatives;
- the proposed use of funds is appropriate; and
- the borrower understands and accepts the collateral risk.
When Should a Borrower Be More Cautious?
Greater caution may be appropriate where:
- income or business cash flows are volatile;
- the proposed EMI leaves little financial buffer;
- borrowing is primarily funding recurring consumption;
- the property is critically important to the family or business;
- the borrower is taking the maximum possible loan without a corresponding requirement;
- future repayment depends heavily on uncertain events; or
- the borrower does not fully understand the loan conditions.
Having eligible collateral answers only one question.
It does not answer whether the borrowing is financially prudent.
Questions to Ask Before Taking a LAP
Before proceeding, a prospective borrower should understand:
Purpose — How much money is actually required, and why?
Property — Is the proposed security acceptable and appropriately documented?
Valuation — What property value has the lender adopted?
LTV — What proportion of that value is being financed?
Eligibility — Is the sanction limited by collateral or repayment capacity?
Rate — How is the interest rate determined and reset?
Tenure — Is the lower EMI worth the additional long-term interest?
Charges — What is the total cost beyond the headline rate?
Prepayment — What flexibility exists to reduce or close the loan early?
Cash Flow — Can the EMI be serviced comfortably during weaker income periods?
Risk — What would happen to the property if repayment difficulties became prolonged?
These questions provide a considerably more complete basis for comparison than simply asking which lender offers the lowest rate.
The Broader Perspective
A Loan Against Property can convert part of the economic value embedded in real estate into usable capital while allowing the borrower to retain ownership of the property, subject to the security created in favour of the lender.
That can make LAP a useful financing instrument for appropriate borrowers and purposes.
But a valuable property should not encourage unnecessary borrowing.
The strength of a LAP lies in the combination of collateral, repayment capacity and appropriate use of funds. Its principal risk arises from exactly the same feature: an important real asset stands behind the debt.
A disciplined borrower should therefore evaluate not merely:
“How much can I borrow against my property?”
but:
“How much do I genuinely need, what will it ultimately cost, can I comfortably repay it, and does the purpose justify putting this property behind the obligation?”
That is the more meaningful foundation for a Loan Against Property decision.
Looking to Discuss an Opportunity?
Connect with Magnet Capital Partners to discuss your requirements and explore how our advisory capabilities may assist.
Disclaimer
This article forms part of Insights — The Magnet Knowledge Series and is intended solely for general informational and educational purposes. It does not constitute investment, financial, legal, tax, regulatory, real estate or other professional advice, nor does it constitute an offer, solicitation, recommendation or assurance in relation to any investment, transaction, product, service or return.
Any information, views, examples, calculations, illustrations, scenarios, projections, estimates or references to valuations, yields, returns, interest rates, financial performance, market conditions or other quantitative or qualitative measures contained in this article are general or illustrative in nature. They should not be interpreted as actual, assured, promised or indicative future outcomes. Actual circumstances and outcomes may differ materially depending upon applicable facts, assumptions, market conditions, commercial considerations, regulatory requirements and other relevant factors.
Readers should undertake their own evaluation and obtain appropriate independent professional advice before making any investment, financial, business, transaction, real estate or other decision. Information contained in this article may change over time and may not reflect subsequent developments. Magnet Capital Partners makes no representation or warranty, express or implied, regarding the accuracy, completeness or continuing relevance of the information contained herein and accepts no liability arising from reliance upon or use of this article, to the extent permitted by applicable law.
Copyright
© Magnet Capital Partners. All rights reserved.
The original editorial content, organisation, structure and presentation of Insights — The Magnet Knowledge Series are protected by applicable copyright laws. No part of this article may be reproduced, republished, distributed, transmitted, adapted or commercially used, in whole or in substantial part, without the prior written permission of Magnet Capital Partners, except as permitted by applicable law. References to third-party information, data, regulations, concepts, terminology, trademarks or other materials remain subject to the rights of their respective owners, where applicable.