Unsecured Business Loans: What to Consider
Access to capital can help a business manage working-capital requirements, respond to opportunities, fund expansion or meet expenditure that cannot conveniently be financed entirely through internal accruals. The challenge is not simply obtaining the money, but determining whether the borrowing is appropriate for the requirement and sustainable for the business.
Unsecured business loans provide one route to such funding without requiring the borrower to pledge specific property or other collateral. This can make them particularly relevant for businesses that either do not have suitable assets to offer as security or prefer not to encumber those assets.
The absence of collateral, however, does not make the borrowing free of consequence. Unsecured lending generally represents greater credit risk for the lender and can consequently carry a higher cost than comparable secured borrowing. The convenience of accessing capital therefore needs to be considered alongside its cost, repayment structure and impact on future cash flows.
Understanding the Unsecured Nature of the Loan
A secured loan is supported by an identified asset or security over which the lender may have recourse in accordance with the financing terms. An unsecured business loan, by contrast, does not ordinarily require such collateral.
For a business owner, this can provide an important advantage. Property or other assets need not necessarily be offered as security merely to raise funds for a business requirement.
But the absence of collateral shifts greater importance to the borrower’s financial and credit profile. Lenders may evaluate factors such as business vintage, turnover, profitability, cash flows, existing borrowings and repayment history when assessing an application.
The important distinction is therefore between being unsecured and being unconditional. A collateral-free facility remains a contractual financial obligation that must be serviced according to its agreed terms.
Convenience Comes at a Cost
The absence of collateral can make unsecured business borrowing more accessible in appropriate circumstances, but it also changes the lender’s risk.
Because there is no identified asset supporting the facility, unsecured business loans may carry higher interest rates than comparable secured facilities. The actual pricing will depend upon the lender, borrower profile, amount, tenure and other applicable factors.
Interest is also not necessarily the only cost.
Processing charges, documentation-related costs, prepayment or foreclosure provisions, penal charges and other applicable fees can influence the overall economics of a facility.
A business should therefore avoid assessing a loan merely by looking at the amount available or the headline interest rate. The more relevant assessment is the total financial commitment created by the borrowing and whether the commercial benefit expected from using the funds reasonably justifies that commitment.
Borrow for a Defined Business Purpose
Borrowing tends to be easier to evaluate when the purpose is clearly identified.
A business may require funds to purchase inventory, bridge a working-capital gap, undertake a planned expansion, acquire equipment, support additional operating capacity or meet another legitimate business requirement.
The proposed use of funds matters because it helps connect the borrowing with the expected source of repayment.
If debt is being taken to finance additional inventory, for example, the business should consider how quickly that inventory is expected to convert into sales and cash. If borrowing supports expansion, the timing and certainty of incremental cash flows deserve attention.
The principle is straightforward: the tenure and repayment structure of the borrowing should, as far as reasonably possible, be considered in relation to the purpose for which the funds are being used.
Debt without a clearly understood purpose can easily become additional financial burden rather than productive business capital.
Avoid the Temptation to Over-Borrow
Availability should not determine necessity.
A lender may be prepared to sanction more than the amount originally contemplated by a business. A pre-approved facility or seemingly manageable EMI can similarly create an incentive to borrow additional funds simply because they are available.
That approach deserves caution.
Every additional amount borrowed creates additional interest cost and repayment obligations. If the incremental funds do not have a productive or necessary use, the business may incur financing costs without generating a corresponding commercial benefit.
Over-borrowing can also reduce future flexibility. Cash flows that could otherwise support operations, investment or unforeseen requirements may become committed to servicing existing debt.
The appropriate borrowing amount is therefore not necessarily the maximum amount available.
A more disciplined approach is to identify the genuine funding requirement, consider an appropriate contingency where justified, and borrow an amount that the business can reasonably service without placing unnecessary pressure on its finances.
Match Repayments with Business Cash Flow
A business can be profitable and still experience periods of cash-flow pressure.
Customers may take time to pay. Inventory may need to be purchased before revenue is realised. Seasonal businesses can experience significant variations in monthly receipts. Expansion may require expenditure well before the resulting income begins to materialise.
For this reason, loan affordability should be assessed against cash flow rather than profitability alone.
Before borrowing, a business may consider how the proposed interest, principal repayments or EMIs will fit alongside salaries, suppliers, taxes, rent and other operating commitments.
Some degree of stress assessment can also be useful. If sales weaken temporarily or collections are delayed, can the business continue servicing the facility without disrupting essential operations?
A repayment obligation that works only when everything proceeds exactly according to plan may leave insufficient margin for ordinary business uncertainty.
Timely Servicing Is Critical
Once a business assumes debt, timely repayment becomes an important financial discipline.
Interest, principal instalments or EMIs should be planned as committed obligations rather than payments to be addressed only after other expenditure has been met.
Delayed or missed repayments can have consequences beyond immediate late-payment charges or penal costs. Repayment behaviour forms part of the borrower’s credit history, and persistent delays, overdue amounts or defaults can adversely affect its credit profile.
A weaker credit record can have implications for future borrowing. When the business subsequently requires working capital, expansion finance or another facility, its historical repayment behaviour may form part of the lender’s assessment.
Businesses should therefore monitor repayment dates carefully and maintain sufficient liquidity to meet obligations when due.
The objective should not merely be to obtain credit, but to preserve the ability to access credit responsibly when it may be needed again.
Consider the Impact of Existing Debt
A new business loan should not be assessed independently of borrowings already on the balance sheet.
Existing term loans, overdrafts, working-capital facilities, equipment finance and other obligations already make claims upon business cash flows. Adding another facility increases the cumulative repayment burden.
This becomes particularly important when several relatively small loans have been accumulated over time. Each EMI may appear manageable individually while their combined effect becomes significant.
Before assuming additional unsecured debt, a business should therefore understand its total financing commitments and the cash flow required to service them.
The question is not simply whether the new EMI can be paid next month. It is whether the overall debt burden remains reasonable relative to the business’s ability to generate cash over the tenure of the borrowing.
Compare More Than the Interest Rate
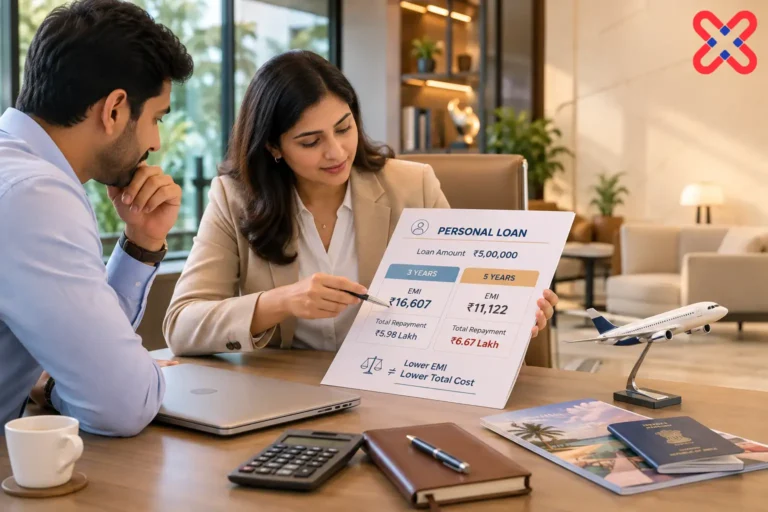
Interest rate is important, particularly because unsecured borrowing can be comparatively expensive, but it should not be the only parameter considered when evaluating alternatives.
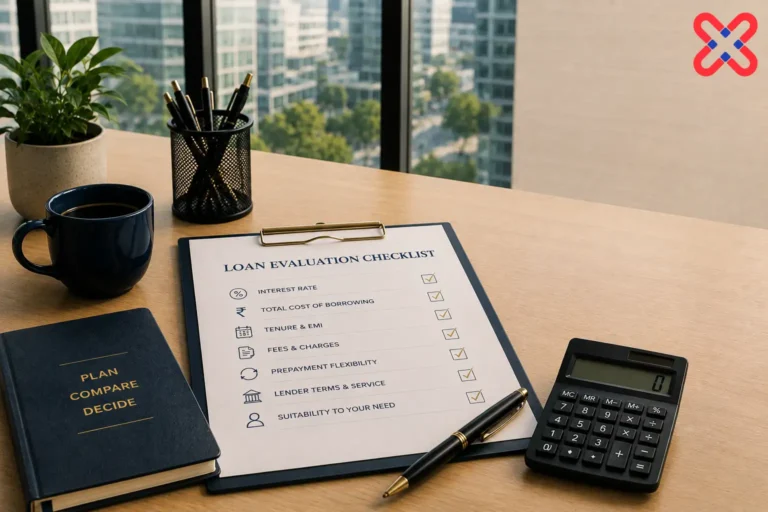
Businesses may also examine the tenure, EMI or repayment structure, processing and other applicable charges, prepayment conditions, foreclosure provisions, documentation requirements and flexibility offered by different lenders.
A lower rate may not necessarily produce the most suitable facility if other terms are restrictive or the repayment structure does not fit the business’s cash cycle.
Conversely, convenience or speed of disbursement should not by itself justify accepting financing whose overall cost or repayment terms are unsuitable.
Comparing facilities on a broader basis helps ensure that the borrowing decision reflects the economics of the complete facility rather than one attractive feature.
Use Unsecured Credit with Financial Discipline
Unsecured business loans can serve a legitimate and useful role in business finance. They can provide access to funds without requiring specific collateral and may help businesses address working-capital needs, investment requirements or growth opportunities.
Their usefulness, however, depends substantially upon how they are used.
The absence of collateral should not be confused with the absence of risk. Unsecured borrowing may carry a higher financing cost, and every facility creates obligations that ultimately have to be met from business cash flows.
A disciplined borrowing decision therefore begins with purpose rather than availability. The business should understand how much capital it genuinely requires, what the borrowing will cost, how it will be repaid and whether sufficient financial flexibility will remain after assuming the obligation.
Borrowing can support a business when capital is deployed productively and debt is serviced responsibly. Over-borrowing, borrowing without a defined purpose or allowing repayment obligations to fall into arrears can produce precisely the opposite outcome.
The objective is not simply to obtain funds when they are available, but to ensure that the debt remains proportionate, purposeful and serviceable throughout its tenure.
Looking to Discuss an Opportunity?
Connect with Magnet Capital Partners to discuss your requirements and explore how our advisory capabilities may assist.
Disclaimer
This article forms part of Insights — The Magnet Knowledge Series and is intended solely for general informational and educational purposes. It does not constitute investment, financial, legal, tax, regulatory, real estate or other professional advice, nor does it constitute an offer, solicitation, recommendation or assurance in relation to any investment, transaction, product, service or return.
Any information, views, examples, calculations, illustrations, scenarios, projections, estimates or references to valuations, yields, returns, interest rates, financial performance, market conditions or other quantitative or qualitative measures contained in this article are general or illustrative in nature. They should not be interpreted as actual, assured, promised or indicative future outcomes. Actual circumstances and outcomes may differ materially depending upon applicable facts, assumptions, market conditions, commercial considerations, regulatory requirements and other relevant factors.
Readers should undertake their own evaluation and obtain appropriate independent professional advice before making any investment, financial, business, transaction, real estate or other decision. Information contained in this article may change over time and may not reflect subsequent developments. Magnet Capital Partners makes no representation or warranty, express or implied, regarding the accuracy, completeness or continuing relevance of the information contained herein and accepts no liability arising from reliance upon or use of this article, to the extent permitted by applicable law.
Copyright
© Magnet Capital Partners. All rights reserved.
The original editorial content, organisation, structure and presentation of Insights — The Magnet Knowledge Series are protected by applicable copyright laws. No part of this article may be reproduced, republished, distributed, transmitted, adapted or commercially used, in whole or in substantial part, without the prior written permission of Magnet Capital Partners, except as permitted by applicable law. References to third-party information, data, regulations, concepts, terminology, trademarks or other materials remain subject to the rights of their respective owners, where applicable.