Loan Prepayment: Reduce EMI or Tenure?
Making a part-prepayment on a loan can reduce the outstanding principal and, consequently, the interest payable over the remaining repayment period.
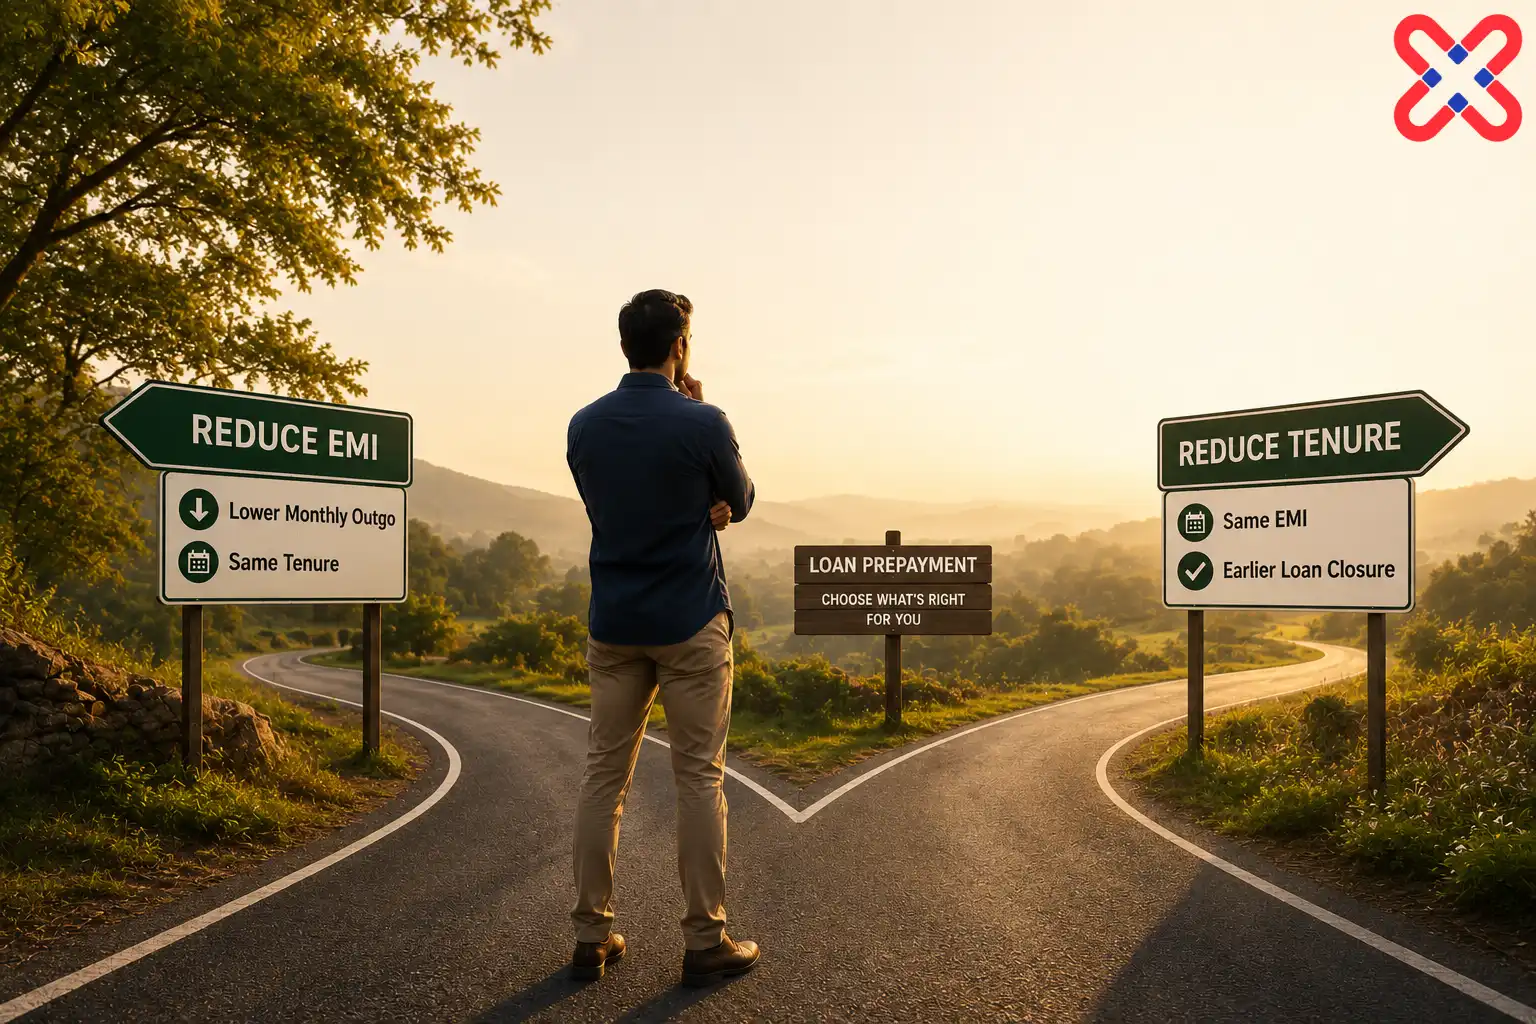
But once a borrower decides to prepay, another important question arises: should the benefit be used to reduce the EMI or shorten the remaining loan tenure?
Both approaches reduce the impact of the outstanding loan, but they serve different financial objectives. Understanding the distinction can help borrowers make a more considered decision.
What Happens When You Prepay a Loan?
Every EMI broadly consists of two components: principal repayment and interest.
Interest is calculated on the outstanding principal. When a borrower makes a part-prepayment, the principal outstanding reduces immediately. Future interest is therefore calculated on a lower amount.
After accounting for the prepayment, depending on the lender and loan terms, the repayment schedule may be revised in one of two principal ways:
- the EMI is reduced while the remaining tenure broadly continues, or
- the EMI is maintained while the remaining tenure reduces.
The financial outcome can be quite different.
Option 1: Reduce the EMI
A borrower may choose to use the prepayment to lower the monthly EMI while retaining approximately the remaining repayment period.
The principal outstanding has reduced, so a smaller monthly instalment may be sufficient to repay the loan over the remaining tenure.
This approach can be useful when the borrower’s priority is improving monthly cash flow.
For example, a lower EMI may provide greater flexibility for household expenses, savings, investments or other financial commitments.
Reducing the EMI can therefore be particularly relevant when monthly repayment obligations have become uncomfortable or when the borrower expects other expenses to increase.
Option 2: Reduce the Tenure
The alternative is to continue paying approximately the existing EMI after making the prepayment.
Because the outstanding principal is now lower while the EMI remains similar, the loan can potentially be repaid sooner.
This generally results in a greater reduction in future interest outgo than simply lowering the EMI, assuming the other loan parameters remain unchanged.
For borrowers who can comfortably continue with their existing EMI, shortening the tenure can therefore be an effective way of accelerating debt repayment.
Why Tenure Reduction Can Save More Interest
Consider two borrowers with identical outstanding loan balances, interest rates and remaining tenures. Both make the same part-prepayment.
The first borrower reduces the EMI but continues repaying over broadly the original remaining tenure.
The second maintains the EMI and uses the prepayment to shorten the tenure.
Although both benefit from the lower outstanding principal, the second borrower stops paying interest earlier because the loan itself ends sooner.
This is why tenure reduction will generally produce greater interest savings than EMI reduction, all else being equal.
The precise savings, however, depend upon the outstanding principal, applicable interest rate, remaining tenure, amount prepaid and lender’s method of recalculating the repayment schedule.
When Reducing EMI May Make Sense
Maximum interest saving is not necessarily every borrower’s only objective.
Reducing the EMI may be appropriate when the borrower wants to create additional room in the monthly budget.
This could be relevant when:
- household expenses have increased;
- income has become less predictable;
- another major financial commitment is approaching;
- the existing EMI represents a significant monthly burden; or
- the borrower wants greater flexibility in managing cash flows.
In such circumstances, accepting somewhat lower interest savings in exchange for greater monthly flexibility may be a reasonable financial choice.
When Reducing Tenure May Make Sense
Tenure reduction may be more appropriate for borrowers whose existing EMI remains comfortably affordable.
It may particularly appeal to someone who wants to:
- become debt-free sooner;
- maximise potential interest savings;
- complete repayment before retirement or another financial milestone;
- reduce long-term financial commitments; or
- redirect the existing EMI towards other goals once the loan is repaid.
The important consideration is whether continuing with the existing EMI leaves sufficient room for other financial requirements.
The Timing of Prepayment Matters
The timing of a prepayment can materially influence its impact.
For many amortising loans, the interest component represents a larger proportion of the EMI during the earlier stages of repayment. As the loan progresses, an increasing proportion of each EMI goes towards principal.
Consequently, a substantial prepayment made relatively early in the loan tenure can potentially avoid more future interest than the same prepayment made close to the end of the loan.
This does not mean that a later prepayment has no value. It simply means borrowers should evaluate the potential savings in the context of the remaining principal and remaining tenure.
Should All Available Savings Be Used for Prepayment?
Not necessarily.
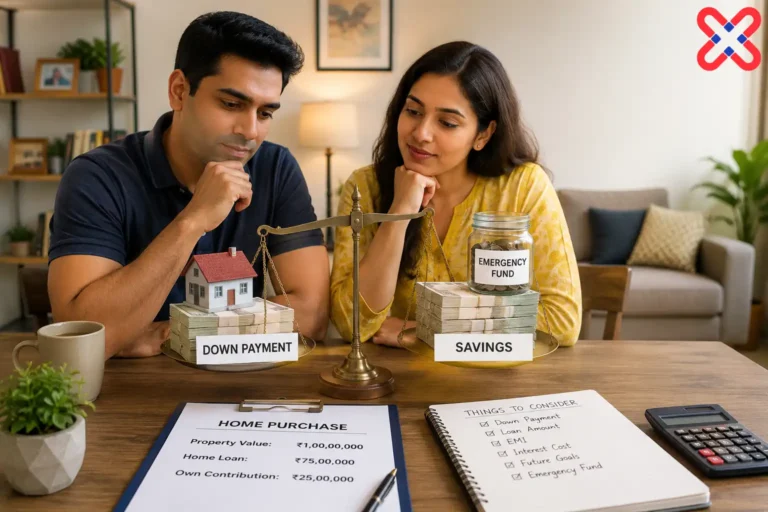
Becoming debt-free faster can be attractive, but borrowers should consider their broader financial position before committing a large amount of available cash towards a loan.
Money used for prepayment generally ceases to be readily available for other requirements.
Before making a substantial prepayment, borrowers may therefore consider whether they have adequate liquidity for:
- emergency expenses;
- near-term household requirements;
- insurance commitments;
- planned major expenditure; and
- other important financial goals.
The decision should balance the benefit of reducing debt against the need to maintain appropriate financial flexibility.
Check the Loan Terms Before Prepaying
Borrowers should also review the terms applicable to their particular loan.
Depending on the type of facility, lender and applicable regulations, there may be conditions relating to part-prepayments, minimum amounts, frequency, procedural requirements or charges.
It is also worth confirming how the lender will treat the prepayment.
A borrower intending to reduce tenure rather than EMI should not simply assume that this will happen automatically. The lender’s revised repayment schedule should be checked after the prepayment is processed.
Compare the Numbers Before Deciding
The difference between reducing EMI and reducing tenure becomes much easier to understand when expressed numerically.
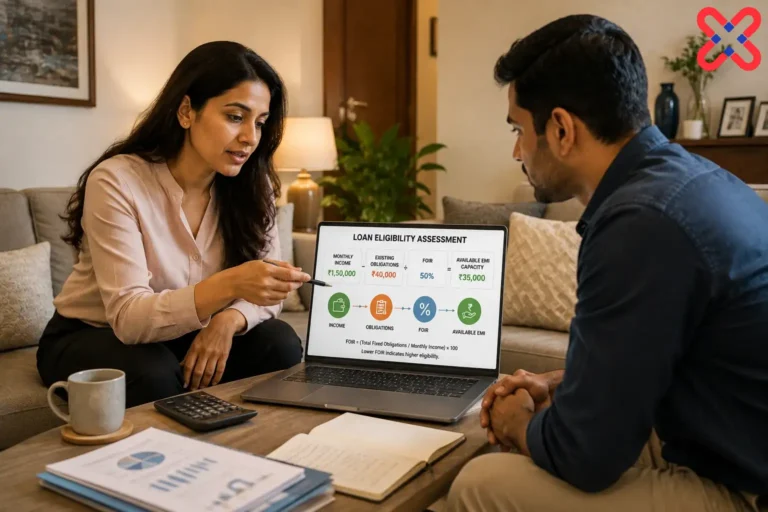
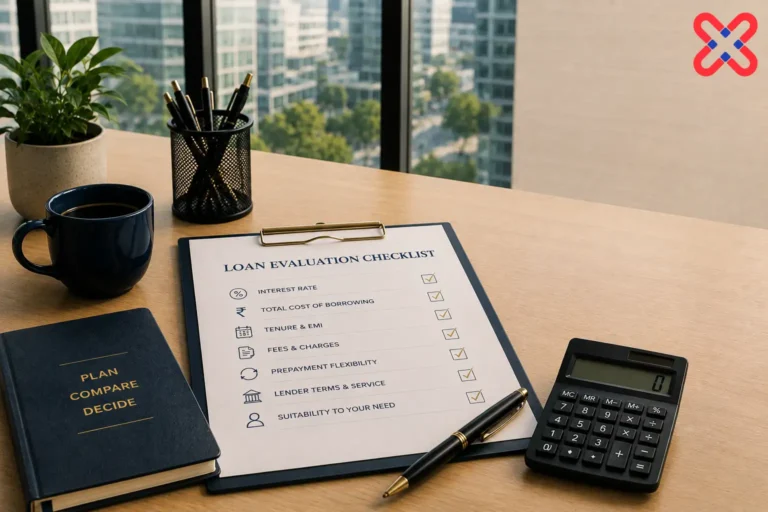
Before choosing between the two options, borrowers can compare:
Current outstanding principal → Prepayment amount → Revised principal → Revised EMI or tenure → Estimated future interest → Potential interest saving
This allows the decision to be based on the actual loan position rather than a general assumption about which alternative is better.
The Loan Prepayment Calculator on Magnet Capital Partners’ Financial Tools section can also be used to estimate how a proposed prepayment may affect the remaining loan.
EMI Reduction or Tenure Reduction?
There is no single choice that suits every borrower.
If the objective is primarily to reduce monthly financial pressure, lowering the EMI may be more appropriate.
If the existing EMI remains affordable and the objective is to repay the loan sooner and potentially maximise interest savings, reducing the tenure will generally be more effective.
The better decision therefore depends not only on mathematics but also on the borrower’s cash flow, liquidity, financial commitments and priorities.
A loan prepayment can create meaningful savings. Deciding how those savings should be used is what turns the prepayment into a broader financial decision.
Looking to Discuss an Opportunity?
Connect with Magnet Capital Partners to discuss your requirements and explore how our advisory capabilities may assist.
Disclaimer
This article forms part of Insights — The Magnet Knowledge Series and is intended solely for general informational and educational purposes. It does not constitute investment, financial, legal, tax, regulatory, real estate or other professional advice, nor does it constitute an offer, solicitation, recommendation or assurance in relation to any investment, transaction, product, service or return.
Any information, views, examples, calculations, illustrations, scenarios, projections, estimates or references to valuations, yields, returns, interest rates, financial performance, market conditions or other quantitative or qualitative measures contained in this article are general or illustrative in nature. They should not be interpreted as actual, assured, promised or indicative future outcomes. Actual circumstances and outcomes may differ materially depending upon applicable facts, assumptions, market conditions, commercial considerations, regulatory requirements and other relevant factors.
Readers should undertake their own evaluation and obtain appropriate independent professional advice before making any investment, financial, business, transaction, real estate or other decision. Information contained in this article may change over time and may not reflect subsequent developments. Magnet Capital Partners makes no representation or warranty, express or implied, regarding the accuracy, completeness or continuing relevance of the information contained herein and accepts no liability arising from reliance upon or use of this article, to the extent permitted by applicable law.
Copyright
© Magnet Capital Partners. All rights reserved.
The original editorial content, organisation, structure and presentation of Insights — The Magnet Knowledge Series are protected by applicable copyright laws. No part of this article may be reproduced, republished, distributed, transmitted, adapted or commercially used, in whole or in substantial part, without the prior written permission of Magnet Capital Partners, except as permitted by applicable law. References to third-party information, data, regulations, concepts, terminology, trademarks or other materials remain subject to the rights of their respective owners, where applicable.