Loan Rejection: Common Reasons and What Next?
A loan rejection can be disappointing, particularly when the borrowing was intended for an important requirement such as purchasing a home, meeting a personal expense or funding a business need.
However, a rejected application does not necessarily mean that the borrower cannot obtain finance in the future.
Lenders assess applications using their own credit policies, eligibility parameters and risk criteria. Understanding what may have affected the decision can help a borrower address potential weaknesses before making another application.
The first response to a rejection should therefore not necessarily be to apply immediately with several other lenders. It can be more useful to understand why the application may not have met the lender’s requirements.
Why Do Lenders Reject Loan Applications?
Loan approval is based on several factors rather than any single number.
Depending on the type of loan, a lender may assess:
- income and its stability;
- existing financial obligations;
- credit history and credit score;
- employment or business profile;
- repayment capacity;
- age and proposed loan tenure;
- banking behaviour;
- loan amount and purpose;
- documentation; and
- property or collateral, where applicable.
A weakness in one area may sometimes be offset by strength elsewhere. In other cases, a particular issue may be significant enough to affect the lender’s decision.
1. Credit Score or Credit History
Credit history is an important part of loan assessment.
A lender may review how a borrower has handled previous and existing credit facilities. Delayed payments, defaults, settlements or other adverse repayment behaviour can affect the assessment.
The credit score provides a summary indicator, but lenders may also examine the underlying credit report.
A borrower with a reasonable score can therefore still face difficulty if the report contains information that causes concern.
Before applying again, it can be useful to review the credit report for both adverse information and possible inaccuracies.
2. Existing EMIs May Be Too High
A borrower may earn a good income and still have limited capacity for another loan.
Existing home loans, personal loans, vehicle loans, business loans and other financial obligations already consume part of monthly income.
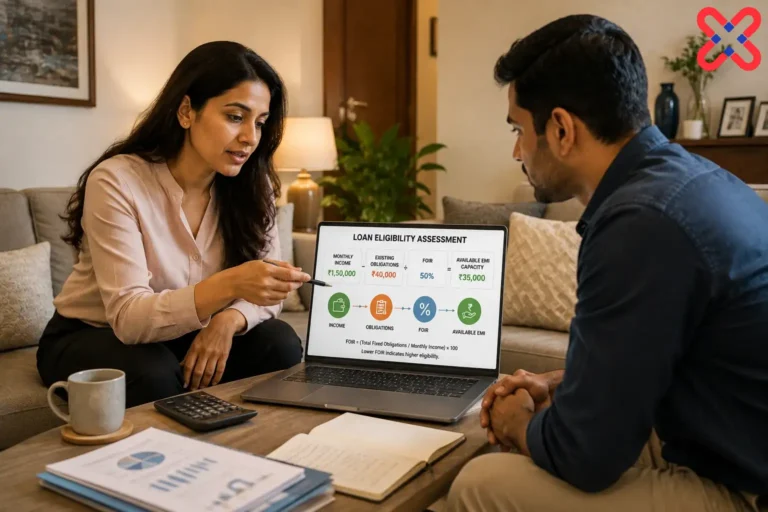
Lenders commonly assess the relationship between income and existing fixed obligations when evaluating the additional EMI a borrower may reasonably service.
If the proposed loan pushes total repayment obligations beyond the lender’s acceptable level, eligibility may reduce or the application may be declined.
This is where FOIR — Fixed Obligation to Income Ratio — can become relevant.
3. Income May Not Support the Requested Loan
Sometimes the issue is not whether the borrower is eligible for a loan, but whether the borrower is eligible for the amount requested.
For example, an applicant may seek a ₹75 lakh home loan while the lender’s assessment supports a substantially lower amount.
Rather than treating this simply as an inability to borrow, the borrower may need to reconsider:
- the loan amount;
- property budget;
- down payment;
- tenure; or
- whether an eligible co-applicant could appropriately be included.
The appropriate solution depends upon the type of loan and the borrower’s circumstances.
4. Income Stability Can Matter
The amount earned is only one aspect of income assessment.
Lenders may also consider its stability and continuity.
For salaried applicants, factors such as employment history, recent job changes and nature of employment may form part of the assessment.
For self-employed applicants and business owners, lenders may examine business vintage, financial performance, banking activity and consistency of income over time.
An applicant with substantial but highly irregular income may therefore be assessed differently from someone with a more predictable earning pattern.
5. Too Many Recent Credit Applications
Applying to numerous lenders simultaneously may appear to increase the probability of obtaining approval, but it is not always an effective strategy.
Applications for credit can result in enquiries appearing on the borrower’s credit report.
A concentration of recent credit enquiries may indicate that the individual is actively seeking borrowing from multiple sources.
This does not automatically result in rejection, but lenders may consider recent credit-seeking behaviour as part of their overall assessment.
It is generally preferable to understand the likely suitability of a loan and lender before submitting multiple applications indiscriminately.
6. Problems With Documentation
A loan can also encounter difficulty because the information required for assessment is incomplete, inconsistent or insufficient.
Depending on the loan, lenders may require documents relating to:
- identity and address;
- income;
- employment;
- business;
- banking activity;
- taxation;
- existing borrowings; and
- property or collateral.
If information across documents does not correspond—for example, significant differences between declared income and banking records—the lender may seek clarification.
Accurate and consistent documentation can therefore be as important as submitting all the required documents.
7. The Property May Be the Issue
For secured lending, particularly home loans and loans against property, borrower eligibility is only one part of the assessment.
The property itself must generally satisfy the lender’s requirements.
Issues may arise in relation to matters such as:
- ownership or title;
- documentation;
- approvals;
- valuation;
- property type;
- location; or
- lender-specific property criteria.
Consequently, a borrower may have adequate income and a satisfactory credit profile but still face difficulty obtaining the desired loan against a particular property.
This distinction is important: borrower eligibility does not automatically establish property eligibility.
8. Age and Loan Tenure
Age can influence the repayment period available to a borrower.
A longer tenure generally reduces the EMI for a given loan amount, while a shorter tenure increases it.
If the applicant’s age restricts the tenure that a lender is prepared to offer, the resulting EMI may become too high relative to the borrower’s assessed repayment capacity.
In a joint application, the ages and profiles of the applicants can also influence how the lender structures the loan.
9. Lender Policies Differ
A rejection by one lender does not necessarily mean every lender will reach the same decision.
Banks, housing finance companies and NBFCs can have different:
- credit policies;
- income assessment methods;
- customer-profile preferences;
- property criteria;
- minimum credit requirements;
- acceptable obligation levels; and
- risk parameters.
A borrower may therefore fit the lending criteria of one institution better than another.
However, this should not be interpreted as a reason to submit applications everywhere. Identifying the underlying reason for the first rejection remains important.
What Should You Do After a Loan Rejection?
Instead of immediately submitting another application, consider reviewing the situation systematically.
Understand the Possible Reason
Where possible, determine what aspect of the application may have affected the lender’s decision.
Was it income? Existing obligations? Credit history? Documentation? The requested amount? Or, in a secured loan, the property itself?
Identifying the likely issue determines what should happen next.
Review Your Credit Report
Check whether the information recorded in your credit report is accurate.
Look for unfamiliar accounts, incorrect outstanding balances, payment information or other discrepancies.
If information is genuinely incorrect, follow the appropriate process with the relevant institution or credit bureau to seek correction.
Reassess Your Existing Obligations
If existing EMIs are limiting eligibility, taking another loan immediately may not address the underlying problem.
Reducing outstanding debt, where financially appropriate, could improve future repayment capacity.
The objective should not simply be to obtain approval but to ensure that the resulting overall debt remains manageable.
Reconsider the Loan Amount
If the amount requested is too high relative to assessed repayment capacity, a smaller loan may be more realistic.
For a home purchase, this could involve adjusting the property budget or increasing the buyer’s contribution while preserving adequate liquidity.
For other loans, it may mean reconsidering the amount actually required.
Correct Documentation Issues
Where the application encountered documentation problems, organise the relevant records before applying again.
Submitting another application with the same inconsistencies is unlikely to resolve the underlying issue.
Should You Apply Again Immediately?
Not necessarily.
If the rejection arose from an issue that remains unchanged, applying immediately elsewhere may simply reproduce the same outcome.
For example, if repayment obligations are already high, another lender may reach a similar conclusion.
Likewise, if the credit report contains an error, it can be preferable to address that issue before making another application.
On the other hand, where the rejection arose primarily because the applicant did not fit a particular lender’s policy, an alternative lender may assess the profile differently.
The appropriate next step therefore depends on why the first application was unsuccessful.
Avoid Chasing Approval at Any Cost
A rejected loan can sometimes cause borrowers to focus entirely on obtaining approval.
That can lead to accepting a loan with an unnecessarily high cost or unsuitable repayment terms simply because another lender is willing to approve it.
Approval alone should not determine whether a loan is appropriate.
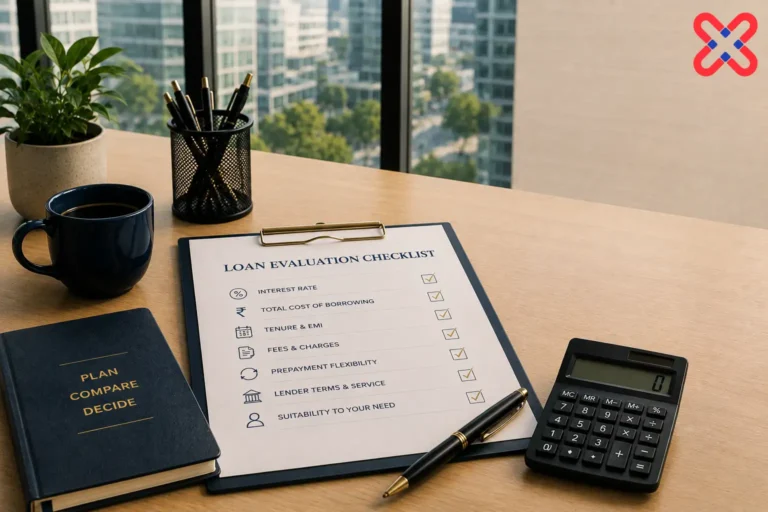
Borrowers should still compare:
- interest rate;
- EMI;
- tenure;
- fees and charges;
- repayment flexibility;
- prepayment conditions; and
- total borrowing cost.
The objective is not merely to find a lender willing to say yes. It is to obtain a loan that remains appropriate and manageable.
A Rejection Can Be Useful Information
A loan rejection should not automatically be viewed as the end of the borrowing process.
It can provide a reason to reassess the applicant’s credit profile, existing obligations, documentation, requested amount or choice of lender.
The most constructive response is usually:
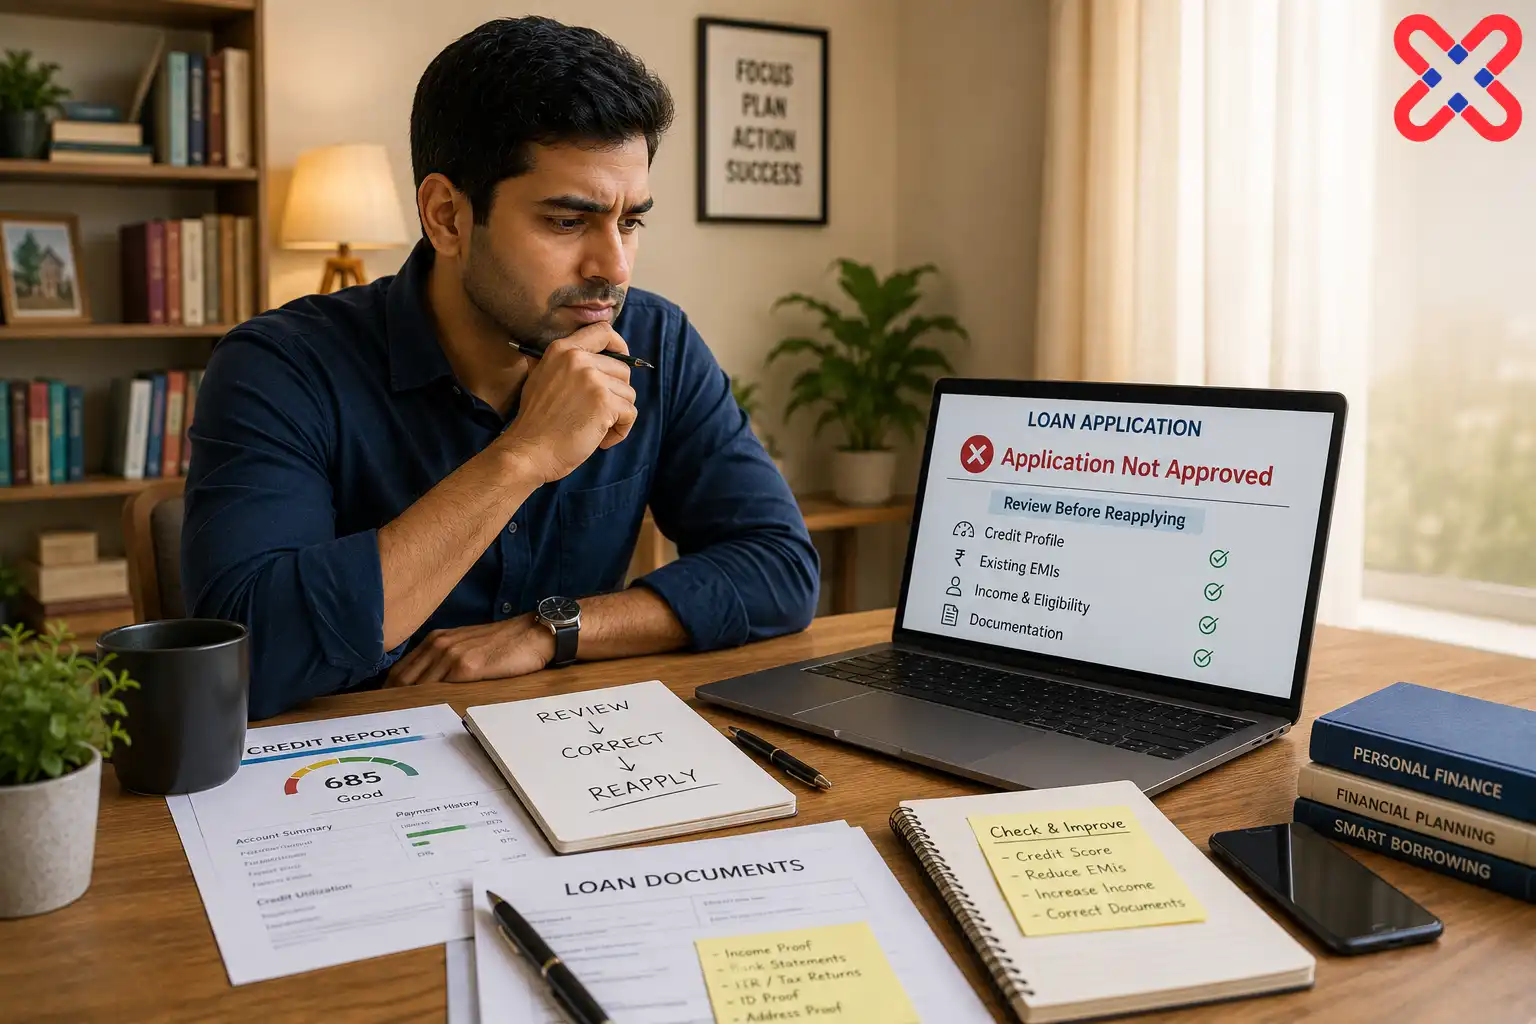
Understand → Review → Correct → Reassess → Apply Appropriately
Addressing the underlying issue before submitting another application can improve the quality of the next application and, more importantly, help ensure that any borrowing undertaken remains financially sustainable.
Looking to Discuss an Opportunity?
Connect with Magnet Capital Partners to discuss your requirements and explore how our advisory capabilities may assist.
Disclaimer
This article forms part of Insights — The Magnet Knowledge Series and is intended solely for general informational and educational purposes. It does not constitute investment, financial, legal, tax, regulatory, real estate or other professional advice, nor does it constitute an offer, solicitation, recommendation or assurance in relation to any investment, transaction, product, service or return.
Any information, views, examples, calculations, illustrations, scenarios, projections, estimates or references to valuations, yields, returns, interest rates, financial performance, market conditions or other quantitative or qualitative measures contained in this article are general or illustrative in nature. They should not be interpreted as actual, assured, promised or indicative future outcomes. Actual circumstances and outcomes may differ materially depending upon applicable facts, assumptions, market conditions, commercial considerations, regulatory requirements and other relevant factors.
Readers should undertake their own evaluation and obtain appropriate independent professional advice before making any investment, financial, business, transaction, real estate or other decision. Information contained in this article may change over time and may not reflect subsequent developments. Magnet Capital Partners makes no representation or warranty, express or implied, regarding the accuracy, completeness or continuing relevance of the information contained herein and accepts no liability arising from reliance upon or use of this article, to the extent permitted by applicable law.
Copyright
© Magnet Capital Partners. All rights reserved.
The original editorial content, organisation, structure and presentation of Insights — The Magnet Knowledge Series are protected by applicable copyright laws. No part of this article may be reproduced, republished, distributed, transmitted, adapted or commercially used, in whole or in substantial part, without the prior written permission of Magnet Capital Partners, except as permitted by applicable law. References to third-party information, data, regulations, concepts, terminology, trademarks or other materials remain subject to the rights of their respective owners, where applicable.