Fixed vs Floating Interest Rates: What to Consider
The interest rate on a loan directly influences the monthly repayment, total interest outgo and, in many cases, the predictability of the borrower’s financial commitments. One important decision borrowers may encounter is whether to choose a fixed or floating interest rate.
While the lower rate may initially appear to be the obvious choice, the appropriate structure depends on several factors, including the type of loan, tenure, prevailing interest-rate environment and the borrower’s preference for certainty or flexibility.
What Is a Fixed Interest Rate?
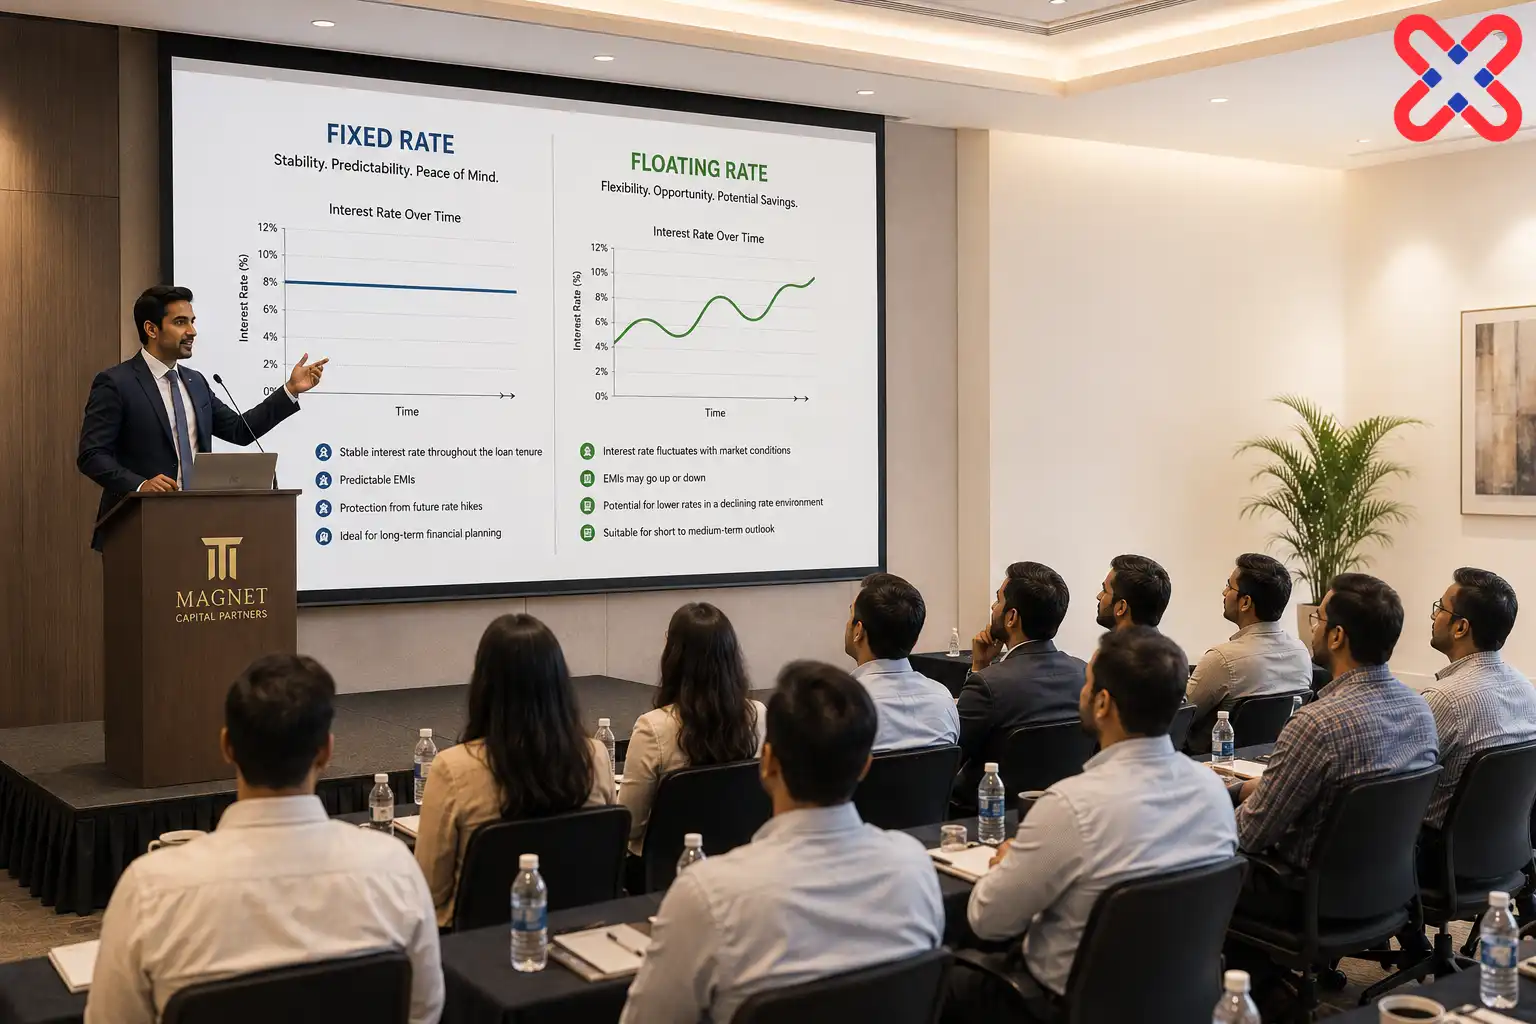
Under a fixed-rate structure, the applicable interest rate generally remains unchanged for the period for which it has been fixed, subject to the lender’s specific terms and conditions.
This can provide greater predictability because the borrower has better visibility over the repayment obligation during that period.
However, borrowers should carefully examine the loan terms. A product described as “fixed” may not necessarily remain fixed for the entire loan tenure. Some lenders may offer a fixed rate only for a specified period before moving to another rate structure.
What Is a Floating Interest Rate?
A floating interest rate can change during the tenure of the loan based on the applicable benchmark and the lender’s pricing framework.
When the applicable rate changes, the lender may adjust the EMI, remaining tenure, or a combination of both, depending on the loan terms and regulatory requirements.
Consequently, the borrower benefits when applicable rates decline but may face higher repayment obligations or a longer tenure when rates increase.
Fixed vs Floating: The Fundamental Difference
The principal distinction is certainty versus variability.
A fixed rate can offer greater repayment visibility. A floating rate allows the borrowing cost to move with changes in the applicable lending rate.
Neither structure is automatically superior in every situation.
A borrower expecting interest rates to rise may value the certainty offered by a suitable fixed-rate structure. Conversely, a borrower choosing a floating rate may benefit if applicable rates subsequently decline.
Predicting future interest-rate movements consistently, however, is difficult. The decision should therefore not depend solely on an expectation about where rates may move next.
Consider the Loan Tenure
Tenure can materially affect the decision.
For a relatively short borrowing period, certainty regarding repayment may be particularly valuable to some borrowers. With longer-tenure loans—especially home loans—the interest-rate environment may change several times during the life of the facility.
Borrowers should therefore consider not merely the rate available today, but how comfortable they would remain if their repayment obligation changed later.
Compare More Than the Headline Rate
Two loan offers should not be compared solely on their advertised interest rates.
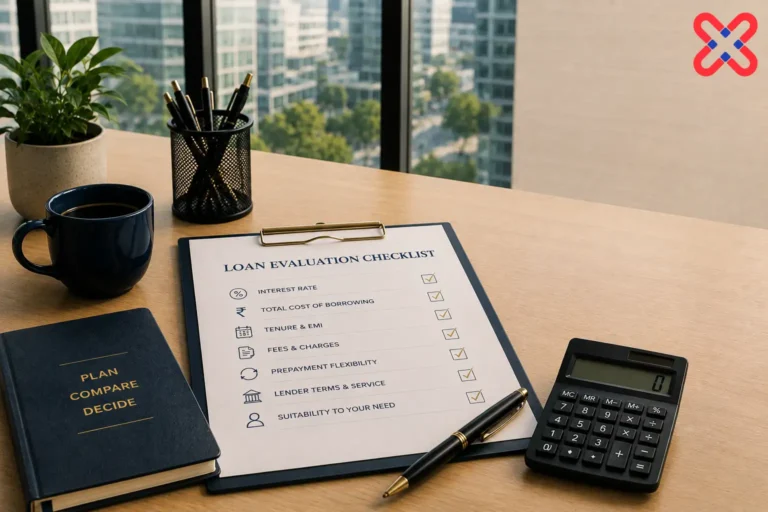
Borrowers should also examine factors such as processing charges, reset provisions, benchmark and spread, prepayment conditions, switching or conversion charges and other applicable costs.
A seemingly small difference in the quoted rate can become significant when applied to a large outstanding principal over several years.
Understand the Effect on EMI and Tenure
Consider a borrower with a long-term loan whose floating interest rate subsequently increases.
The immediate assumption may be that the EMI will rise. In practice, depending upon the lender and loan structure, the lender may instead extend the remaining tenure or use a combination of increased EMI and tenure.
An extended tenure can substantially affect the total interest ultimately paid.
Borrowers should therefore periodically review not only their EMI but also the outstanding principal, applicable rate and remaining tenure.
Can Borrowers Switch Between Fixed and Floating Rates?
Depending upon the lender and the loan product, borrowers may have the option to change the interest-rate structure.
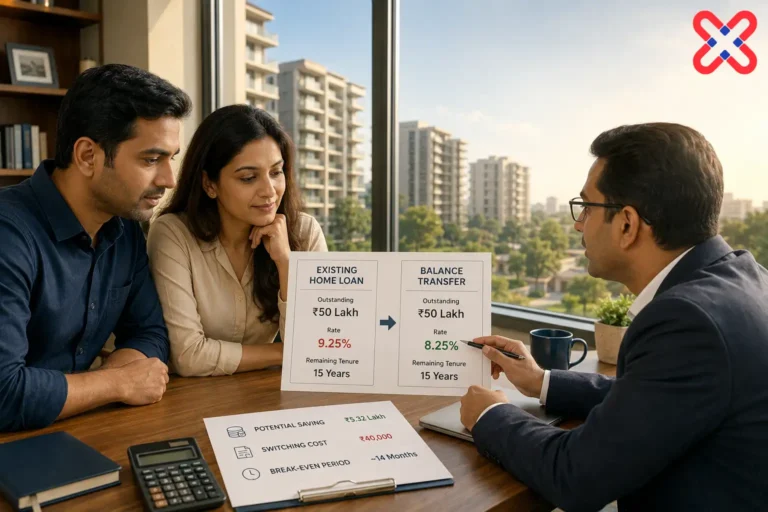
Such a conversion may involve charges and revised terms. The financial benefit of switching should therefore be assessed after considering all associated costs rather than merely comparing the old and new rates.
Similarly, borrowers considering transferring their loan to another lender should evaluate the overall savings after transfer-related costs.
Which Option Should a Borrower Choose?
The answer depends upon the borrower’s circumstances.
Someone who places a high value on repayment certainty may prefer an appropriate fixed-rate structure even if its initial pricing is somewhat different. Another borrower with sufficient financial flexibility may be comfortable accepting fluctuations associated with a floating rate.
The decision should take into account:
- Current fixed and floating rates available
- Loan amount and remaining tenure
- Ability to absorb an increase in EMI
- Possibility of tenure extension
- Applicable benchmark and reset mechanism
- Conversion and prepayment conditions
- Overall cost of borrowing
The objective is not simply to identify the lowest rate displayed today. It is to select a borrowing structure that remains manageable across the expected life of the loan.
Looking Beyond the Interest Rate
Interest rate is an important component of any loan, but it should be considered alongside eligibility, repayment capacity, fees, tenure and loan terms.
Understanding how fixed and floating rates behave allows borrowers to compare loan offers more meaningfully and make financing decisions with greater clarity.
For a long-tenure commitment in particular, the structure of the interest rate can matter almost as much as the rate itself.
Looking to Discuss an Opportunity?
Connect with Magnet Capital Partners to discuss your requirements and explore how our advisory capabilities may assist.
Disclaimer
This article forms part of Insights — The Magnet Knowledge Series and is intended solely for general informational and educational purposes. It does not constitute investment, financial, legal, tax, regulatory, real estate or other professional advice, nor does it constitute an offer, solicitation, recommendation or assurance in relation to any investment, transaction, product, service or return.
Any information, views, examples, calculations, illustrations, scenarios, projections, estimates or references to valuations, yields, returns, interest rates, financial performance, market conditions or other quantitative or qualitative measures contained in this article are general or illustrative in nature. They should not be interpreted as actual, assured, promised or indicative future outcomes. Actual circumstances and outcomes may differ materially depending upon applicable facts, assumptions, market conditions, commercial considerations, regulatory requirements and other relevant factors.
Readers should undertake their own evaluation and obtain appropriate independent professional advice before making any investment, financial, business, transaction, real estate or other decision. Information contained in this article may change over time and may not reflect subsequent developments. Magnet Capital Partners makes no representation or warranty, express or implied, regarding the accuracy, completeness or continuing relevance of the information contained herein and accepts no liability arising from reliance upon or use of this article, to the extent permitted by applicable law.
Copyright
© Magnet Capital Partners. All rights reserved.
The original editorial content, organisation, structure and presentation of Insights — The Magnet Knowledge Series are protected by applicable copyright laws. No part of this article may be reproduced, republished, distributed, transmitted, adapted or commercially used, in whole or in substantial part, without the prior written permission of Magnet Capital Partners, except as permitted by applicable law. References to third-party information, data, regulations, concepts, terminology, trademarks or other materials remain subject to the rights of their respective owners, where applicable.