Real Estate Investment: Beyond Price
The purchase price of a real estate asset is immediately visible. The economics of owning it are considerably broader.
For an investor, acquisition price represents the amount required to enter the investment, but it does not by itself establish value, income potential or eventual return. Two properties acquired at apparently similar valuations can perform very differently because of their location, occupancy, tenant quality, operating costs, capital requirements and future marketability.
A more considered real estate investment assessment therefore looks beyond the transaction price and examines the characteristics that can influence the asset throughout the period of ownership.
Location Is More Than an Address
Location remains one of the fundamental considerations in real estate, but its relevance extends beyond the name or reputation of a particular area.
Accessibility, surrounding infrastructure, connectivity, employment centres, residential catchments and the availability of complementary commercial or social infrastructure can all influence demand for a property. The importance of individual factors will vary significantly across asset classes.
Location should also be considered dynamically rather than only in its present form. Infrastructure development, changing business districts, evolving residential patterns and new competing supply can alter the relative attractiveness of an area over time.
An investor therefore needs to consider both the location that exists today and the factors that may influence its relevance during the intended investment horizon.
Asset Quality Influences Long-Term Economics
A property’s physical characteristics can materially affect its investment performance.
Building age, construction quality, layout, specifications, maintenance standards and the condition of common areas may influence both occupier demand and future expenditure. An asset that appears attractively priced may require significant investment after acquisition to maintain its competitiveness.
The assessment can become particularly important when comparing an older property with a newer asset. A lower acquisition price may initially appear advantageous, but anticipated repairs, refurbishment, equipment replacement or compliance-related expenditure can change the economics considerably.
Investors should therefore distinguish between the price paid for the property and the capital that may subsequently be required to preserve or improve it.
Occupancy Requires Closer Examination
For an income-producing property, occupancy is an important indicator, but the headline occupancy percentage does not tell the complete story.
An asset with high occupancy may appear secure, yet its income profile can depend heavily upon the quality of tenants, remaining lease periods, concentration among a small number of occupiers and the terms upon which space has been leased.
Conversely, lower occupancy is not automatically evidence of a weak investment. In certain circumstances, vacancy may provide an opportunity for repositioning or improved leasing, although such a strategy introduces execution and market risk.
The more relevant assessment is therefore not simply whether the property is occupied, but how sustainable and diversified its occupancy and associated income appear to be.
Rental Income Should Be Viewed in Context
Rental income is often central to the investment case for commercial and other income-producing real estate.
However, headline rent should not be considered independently of the contractual and commercial framework supporting it.
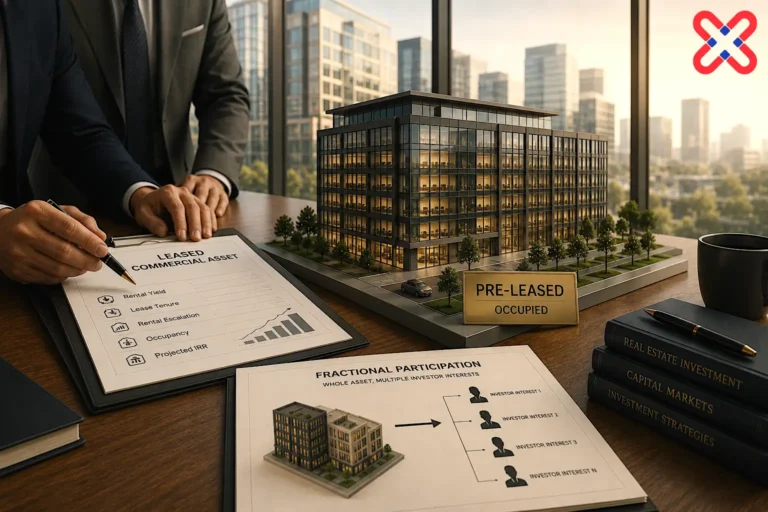
Lease tenure, escalation provisions, security deposits, rent-free periods, renewal conditions and other contractual terms can influence the quality and predictability of income. The creditworthiness and business stability of significant tenants may also deserve consideration.
Investors should additionally distinguish between gross rental receipts and the income that remains after expenses attributable to ownership.
A property generating higher headline rent may not necessarily produce superior economics if it also carries substantially higher operating or maintenance requirements.
Operating Costs Affect the Real Return
Real estate ownership involves expenditure as well as income.
Depending upon the asset and contractual arrangements, costs may arise from maintenance, repairs, insurance, property management, common areas, periods of vacancy and other ownership responsibilities. Certain expenses may be recoverable from occupiers, while others may remain with the owner.
Capital expenditure can create a further distinction.
Routine operating expenditure maintains the property in its normal course, whereas larger capital requirements may arise periodically to replace equipment, refurbish space or reposition the asset.
Understanding these costs helps an investor move from a headline income perspective towards a clearer assessment of the property’s underlying economics.
Tenant Quality and Concentration Matter
A leased property derives much of its investment value from the cash flows generated by its occupiers.
The quality of those cash flows can therefore depend partly upon the tenants responsible for paying the rent.
A well-established occupier under an appropriate lease structure may provide greater visibility than an equivalent rental stream dependent upon a tenant with uncertain financial capacity. At the same time, even strong tenants can create concentration risk if a substantial proportion of the property’s income depends upon a single occupier.
A diversified tenant base may reduce that dependence, although diversification alone does not guarantee income stability.
The relevant assessment combines tenant quality, concentration, lease expiry profile and the likelihood that space can be re-let on reasonable terms if an existing tenant vacates.
Liquidity Is Different in Real Estate
Real estate is generally less liquid than many financial assets.
Selling a property can require time for marketing, negotiations, due diligence, documentation and completion. The achievable price can also depend significantly upon market conditions at the time a sale is required.
This characteristic becomes particularly relevant when an investor may need access to capital within a defined period.
A property that appears attractive from an income or appreciation perspective may be less suitable if the investor requires substantial liquidity or has a relatively short investment horizon.
Liquidity should therefore be considered at the time of acquisition rather than only when the decision to sell has already arisen.
Exit Potential Begins at Acquisition
Investment analysis often concentrates naturally on entering a transaction. Yet the eventual exit deserves consideration before the acquisition is completed.
The potential pool of future buyers can be influenced by asset size, location, quality, tenancy, ticket size, market positioning and prevailing investment preferences. An unusual property may offer attractive economics to a particular investor while simultaneously appealing to a narrower universe of future purchasers.
This does not necessarily make the investment unattractive. It simply means that exit flexibility should form part of the initial assessment.
Investors may also consider whether value creation depends primarily upon market appreciation or whether improvements in occupancy, rental profile, asset quality or positioning could strengthen the property independently.
A clearly understood investment thesis makes it easier to evaluate whether the asset continues to justify ownership as circumstances change.
Investment Horizon Shapes the Decision
Real estate investments can behave differently depending upon how long they are held.
An investor seeking relatively stable income may evaluate an asset differently from one seeking redevelopment, repositioning or capital appreciation. Similarly, an investment requiring substantial initial improvement may be unsuitable for a short holding period even if its longer-term prospects appear attractive.
The investment horizon can influence the importance assigned to current income, lease expiries, capital expenditure, financing structure and potential exit conditions.
It can also affect the investor’s ability to withstand periods of vacancy, temporary market weakness or delays in executing a value-creation strategy.
The property should therefore be considered not only in terms of what it is, but also in relation to what the investor expects it to achieve and over what period.
Looking Beyond the Price
Price remains an essential part of every real estate investment decision, but it acquires meaning only when considered alongside the characteristics of the asset being acquired.
Location, physical quality, occupancy, tenant profile, rental structure, operating costs, capital requirements, liquidity and exit potential can materially influence investment outcomes after the acquisition has been completed.
A lower-priced asset is not necessarily inexpensive if it carries substantial hidden expenditure or weak income visibility. Equally, a higher acquisition price may sometimes reflect characteristics that contribute to stronger occupancy, better-quality income or greater future marketability.
The objective is therefore not simply to identify property available at an attractive price.
It is to understand what the investor is receiving for that price, what additional commitments ownership may require and how the asset fits within the investor’s objectives, financial capacity and intended holding period.
Looking to Discuss an Opportunity?
Connect with Magnet Capital Partners to discuss your requirements and explore how our advisory capabilities may assist.
Disclaimer
This article forms part of Insights — The Magnet Knowledge Series and is intended solely for general informational and educational purposes. It does not constitute investment, financial, legal, tax, regulatory, real estate or other professional advice, nor does it constitute an offer, solicitation, recommendation or assurance in relation to any investment, transaction, product, service or return.
Any information, views, examples, calculations, illustrations, scenarios, projections, estimates or references to valuations, yields, returns, interest rates, financial performance, market conditions or other quantitative or qualitative measures contained in this article are general or illustrative in nature. They should not be interpreted as actual, assured, promised or indicative future outcomes. Actual circumstances and outcomes may differ materially depending upon applicable facts, assumptions, market conditions, commercial considerations, regulatory requirements and other relevant factors.
Readers should undertake their own evaluation and obtain appropriate independent professional advice before making any investment, financial, business, transaction, real estate or other decision. Information contained in this article may change over time and may not reflect subsequent developments. Magnet Capital Partners makes no representation or warranty, express or implied, regarding the accuracy, completeness or continuing relevance of the information contained herein and accepts no liability arising from reliance upon or use of this article, to the extent permitted by applicable law.
Copyright
© Magnet Capital Partners. All rights reserved.
The original editorial content, organisation, structure and presentation of Insights — The Magnet Knowledge Series are protected by applicable copyright laws. No part of this article may be reproduced, republished, distributed, transmitted, adapted or commercially used, in whole or in substantial part, without the prior written permission of Magnet Capital Partners, except as permitted by applicable law. References to third-party information, data, regulations, concepts, terminology, trademarks or other materials remain subject to the rights of their respective owners, where applicable.