Choosing the Right Loan: Beyond Interest Rates
Choosing a loan often begins with one seemingly straightforward question: What is the interest rate?
It is an important question, but rarely the only one that matters.
Whether the requirement is for a home loan, loan against property, business loan or personal loan, the suitability of a borrowing arrangement depends on several interconnected factors. Interest rate influences the cost of borrowing, but tenure, repayment structure, fees, flexibility, lender terms and the borrower’s own financial circumstances can materially affect the overall outcome.
A well-considered borrowing decision therefore requires looking beyond the headline rate and understanding the loan in its entirety.
The Interest Rate Is Only the Starting Point
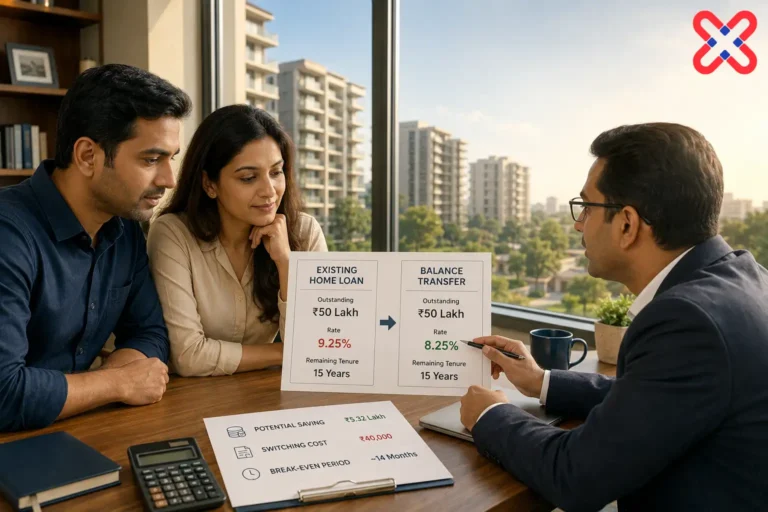
Interest rates provide an immediate basis for comparing loan offers. Even a relatively small difference in rates can have a meaningful impact on interest outgo over a long tenure.
However, the lowest quoted rate does not automatically make a particular loan the most suitable option.
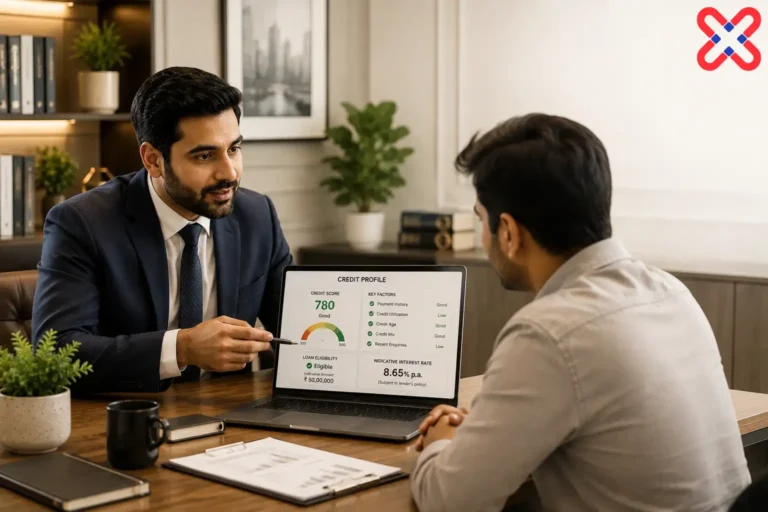
The rate ultimately available to a borrower may depend on factors including credit profile, income, employment or business characteristics, loan amount, tenure, security offered and the lender’s prevailing credit criteria. Advertised rates may represent the starting point of a wider pricing range rather than the rate applicable to every borrower.
The appropriate comparison is therefore between actual offers available to the borrower, considered alongside their respective terms and conditions.
Look at the Overall Cost of Borrowing
A loan can involve costs beyond interest.
Depending upon the product and lender, these may include processing fees, administrative charges, valuation or legal expenses, insurance-related costs and other applicable charges.
Two loans carrying similar interest rates may consequently have different overall costs.
Borrowers should understand the principal charges associated with each proposal and consider them as part of the financing decision rather than assessing the interest rate in isolation.
Balance EMI and Tenure
Loan tenure has a direct relationship with both monthly affordability and total interest outgo.
A longer tenure generally reduces the monthly instalment, making repayment easier to accommodate within current cash flows. At the same time, extending repayment over a longer period can increase the aggregate interest paid during the life of the loan.
A shorter tenure can reduce total interest outgo but results in a higher monthly repayment commitment.
The objective should therefore not simply be to obtain the lowest possible EMI. It should be to establish a repayment structure that remains comfortable without unnecessarily extending the borrowing period.
Understand Fixed and Floating Rates
The nature of the interest rate can also influence the borrowing experience.
A fixed-rate arrangement can provide greater certainty over repayments for the period during which the rate remains fixed. A floating-rate loan, on the other hand, can change in response to the applicable benchmark and the terms governing the facility.
Changes in floating rates may affect the EMI, tenure or both, depending upon the loan structure and lender policy.
Neither structure is inherently preferable in every circumstance. The appropriate choice depends on the product, prevailing terms, the borrower’s preference for repayment certainty and the ability to accommodate future changes.
Consider Prepayment Flexibility
Financial circumstances do not remain static throughout the life of a loan.
Income may increase, a business may generate additional surplus, an asset may be sold or other funds may become available. A borrower may consequently wish to repay part or all of a loan earlier than originally anticipated.
Prepayment and foreclosure provisions can therefore be important, particularly for longer-tenure borrowing.
Understanding whether partial prepayments are permitted, whether conditions apply and how an early repayment would affect the outstanding tenure or instalment provides a more complete picture of the flexibility offered by the loan.
Evaluate the Lender, Not Just the Loan
Borrowing establishes a relationship that can continue for several years.
Service quality, documentation processes, communication, digital access, responsiveness and ease of obtaining account-related information can all influence that experience.
For secured facilities in particular, borrowers should also understand documentation requirements, security-related procedures and the process applicable upon repayment and closure of the facility.
Price matters, but efficient servicing and clear processes can also carry meaningful value over the life of a loan.
Compare Like with Like
Meaningful comparison requires consistency.
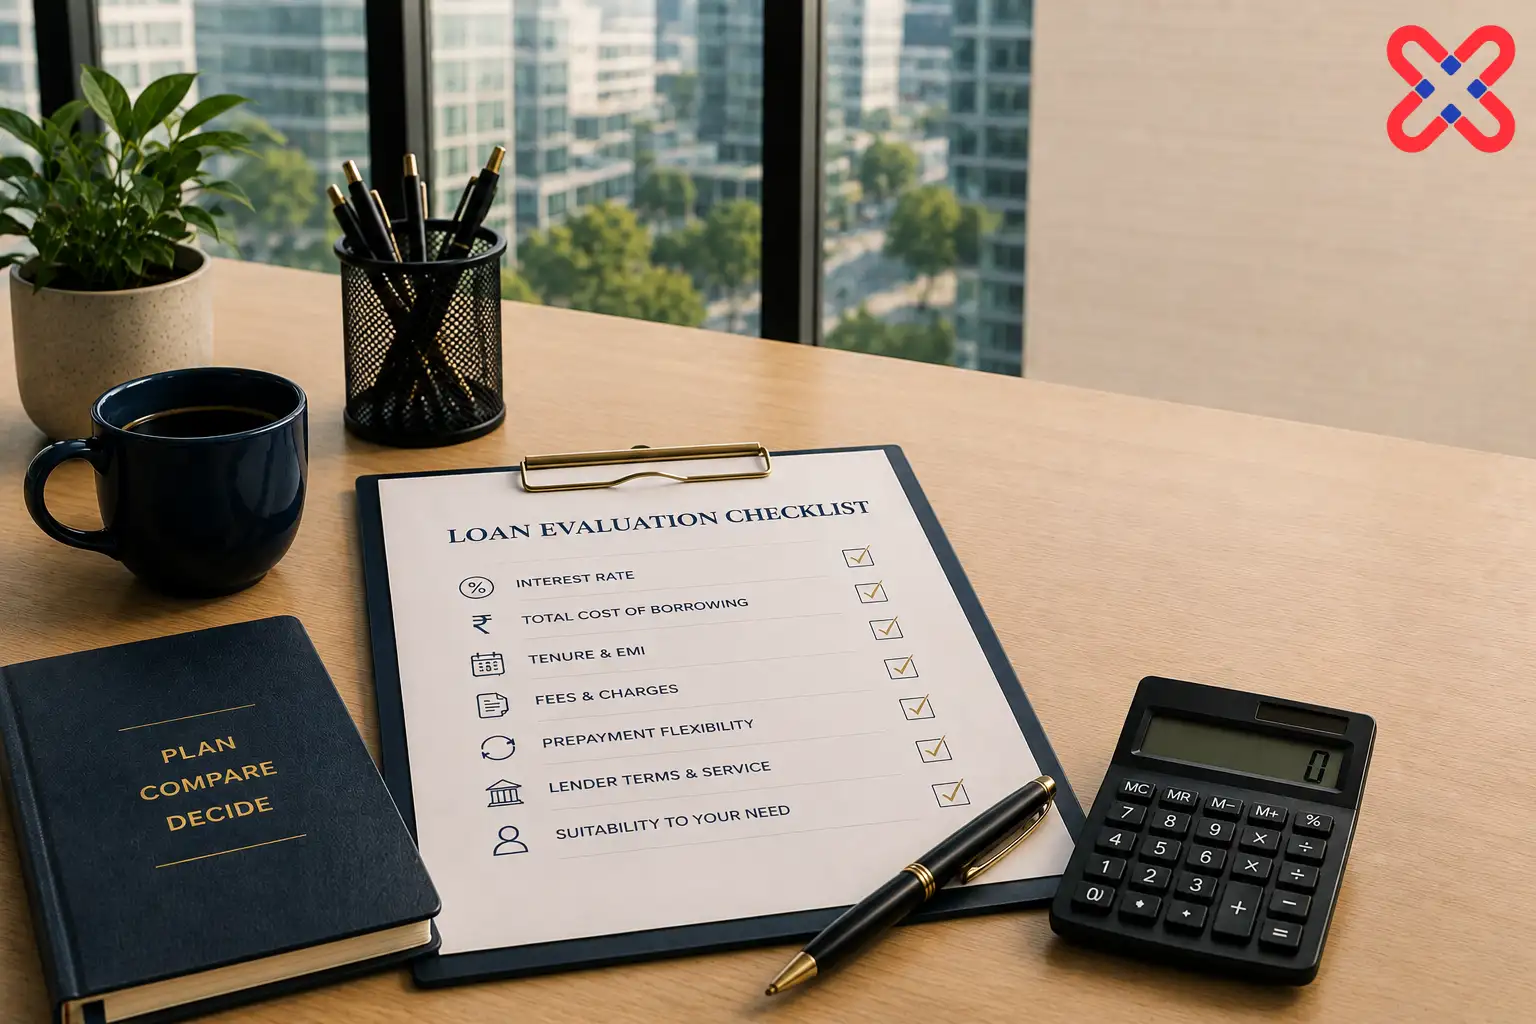
When evaluating alternatives, borrowers should ideally compare proposals on broadly equivalent parameters, including:
- loan amount;
- tenure;
- applicable interest rate and its nature;
- estimated EMI;
- principal fees and charges;
- prepayment or foreclosure provisions;
- security or collateral requirements, where applicable;
- documentation requirements; and
- other material terms and conditions.
A structured comparison helps prevent one attractive feature from overshadowing less obvious differences elsewhere in the proposal.
Match the Loan to the Requirement
Different borrowing requirements call for different financing solutions.
A home purchase, liquidity requirement against an existing property, business funding need and short-term personal requirement are fundamentally different circumstances. The appropriate product, lender and repayment structure should reflect the purpose of borrowing as well as the borrower’s financial position.
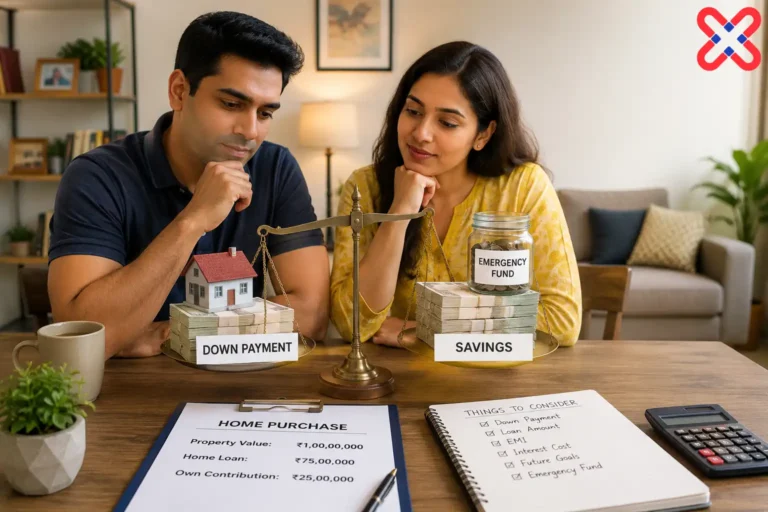
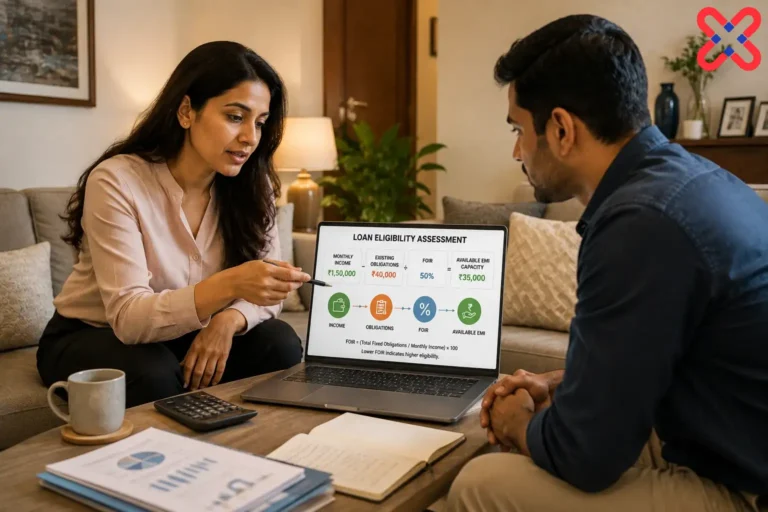
The amount sanctioned should also not automatically determine the amount borrowed. Eligibility represents what a lender may be prepared to provide; affordability reflects what the borrower can comfortably service.
Maintaining that distinction is central to prudent borrowing.
Make the Decision in Context
The right loan is not necessarily the one displaying the lowest number in an interest-rate comparison.
It is the arrangement whose cost, repayment commitment, tenure, flexibility and terms collectively suit the borrower’s circumstances and objectives.
Looking beyond the headline rate allows borrowers to compare financing alternatives more meaningfully and make decisions with a clearer understanding of both immediate affordability and longer-term implications.
For an important financial commitment, that broader perspective can matter as much as the rate itself.
Looking to Discuss an Opportunity?
Connect with Magnet Capital Partners to discuss your requirements and explore how our advisory capabilities may assist.
Disclaimer
This article forms part of Insights — The Magnet Knowledge Series and is intended solely for general informational and educational purposes. It does not constitute investment, financial, legal, tax, regulatory, real estate or other professional advice, nor does it constitute an offer, solicitation, recommendation or assurance in relation to any investment, transaction, product, service or return.
Any information, views, examples, calculations, illustrations, scenarios, projections, estimates or references to valuations, yields, returns, interest rates, financial performance, market conditions or other quantitative or qualitative measures contained in this article are general or illustrative in nature. They should not be interpreted as actual, assured, promised or indicative future outcomes. Actual circumstances and outcomes may differ materially depending upon applicable facts, assumptions, market conditions, commercial considerations, regulatory requirements and other relevant factors.
Readers should undertake their own evaluation and obtain appropriate independent professional advice before making any investment, financial, business, transaction, real estate or other decision. Information contained in this article may change over time and may not reflect subsequent developments. Magnet Capital Partners makes no representation or warranty, express or implied, regarding the accuracy, completeness or continuing relevance of the information contained herein and accepts no liability arising from reliance upon or use of this article, to the extent permitted by applicable law.
Copyright
© Magnet Capital Partners. All rights reserved.
The original editorial content, organisation, structure and presentation of Insights — The Magnet Knowledge Series are protected by applicable copyright laws. No part of this article may be reproduced, republished, distributed, transmitted, adapted or commercially used, in whole or in substantial part, without the prior written permission of Magnet Capital Partners, except as permitted by applicable law. References to third-party information, data, regulations, concepts, terminology, trademarks or other materials remain subject to the rights of their respective owners, where applicable.